Pertuity Direct – where is the p2p lending part?


Invest In People with Pertuity Direct.
Initially while browsing the PertuityDirect.com and the related NationalRetailFund.com site I was a bit puzzled where the peer to peer lending aspect is to be found? I learned:

  • Lenders buy shares
  • Borrowers credit information details are never shared. Only Pertuity Direct knows them
  • There is no auction
  • Interest rates are set by Pertuity Direct

Then I read the National Retail Fund II prospectus and learned that the Fund is allowed to do other investments then funding loans of Pertuity Direct borrowers. It may:

  • buy T-Bills, money market funds and other cash equivalents
  • buy bundled consumer note securities, even if part of them is deliquent

The NationalRetailFund website explains:

How is this related to Pertuity Direct?

Pertuity Direct is a separate entity and is one of the fund’s service providers and acts in an administrative role. They underwrite and originate borrower loans. Those loans are an investment option for this fund.

On the same FAQ page I then found what this all has to do with p2p lending:

Where is the ‘Social’ aspect in all of this?

If you choose, you have the option to engage in the social lending network associated with the borrowers within the funds. By selecting the option, you will be able to see the various borrowers in the funds, get to read their stories and track their progress over time. You will also have the ability to engage directly with any borrower or group of borrowers that you find compelling and help them accomplish their goals with a rewards program.

Lenders can use so called Pertuity Bucks, which they receive free upon sign up, to reward borrowers whose stories they find compelling. The balance of the borrower is reduced by the amount of Pertuity Bucks the borrower receives.

My review summary of the p2p lending aspect of Pertuity Direct

While it may be a smart construct in respect to overcoming regulation hurdles it offers much less direct peer to peer interaction between lender and borrower.

  1. Pertuity Direct decides which loans get approved
  2. Pertuity Direct sets the interest rates
  3. The fund decides on the investment strategy in detail
  4. Interaction takes place only through the Pertuity Bucks community feature

But let’s see how the concept develops and what borrowers and lenders think about it.

What is your take on this, dear reader?

Pertuity Direct launch

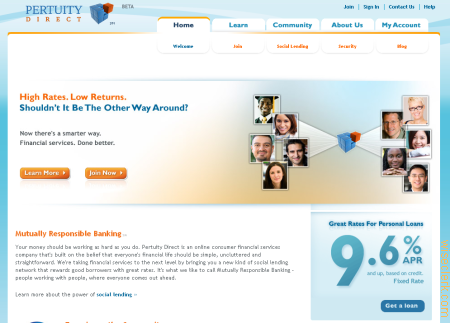
The new p2p lending service PertuityDirect.com is now online. The concept Pertuity Direct uses is new. Lenders pay into the “National Retail Fund” which is a “social lending mutual fund”.

If I understand the concept correctly, you do not choose individual borrowers you want to lend to, but rather a group of borrowers with similar parameters by buying share of a fund – but if you want to, there is the option for individual selection (similar to Lending Club). Have not grasped yet how the individual selection is supposed to work when you by shares of the fund?
The initial minimum investment amount is 1,000 US$ per lender.

A so far unheard feature is that it Pertuity Direct allows  early withdrawel of funds by lenders (2% withdrawal fee for withdrawals in first year of investment). Another new feature I found while reading the multiple page fund prospectus, is that lenders can set up an automatic investment plan, making monthly or quarterly investments.

Interest rates of the loans are set in the range from 8.9% to 17.9%. Pertuity Direct accepts only borrowers with a FICO credit score of 660 or higher. Update: In fact the prospectus of the National Retail Fund II states that Pertuity will invest over 80% of the money in loans whose borrower’s have a credit score of at least 720.

One advantage for borrowers is that – if approved – they get the loan faster than on other p2p lending sites, since there is no bidding or auction just the evaluation and approval process. Pertuity claims that typically borrowers will receive the money within 2 – 3 business days.

Borrower Fees

1-2% closing fee (depending on credit score)
$15 failed payment fee
$15 late payment fee (on average, may be slightly lower/higher in some states)
1% Electronic Funds Transfer discount

Lender Fees

Currently, the first year expense estimate is 3.17%, or $32 a year for every $1,000 invested. Fees are estimated based on the aggregate size of the fund.

This estimate assumes a monthly average fund size of $12 million during the first year.

While I browse the site for more information, in the meantime check out CEO Kim Muhato’s post on the blog. Excerpt:

Pertuity Direct’s Social Lending Network is different from anything else in the market. The social lending networks we are building will expand to specific affinity groups borrowing from and lending to each other; for example, professional associations like doctors and firefighters, small business owners in specific geographic regions, and university alumni groups etc. We call it Mutually Responsible Banking. Learn more about Pertuity Direct’s Social Lending Network here.

Our team is comprised of executives that have collectively worked in the U.S. financial services arena for a few decades with companies like Capital One, E*TRADE and PNC. We have executives who have experience building innovative and scalable web-based financial products, executives who have managed consumer credit and multi-million dollar loan portfolios, as well as brilliant engineers and systems architects. Our team is dedicated to changing the consumer finance landscape and loves to be on the cutting edge of financial innovation.

More on Smava Poland launch

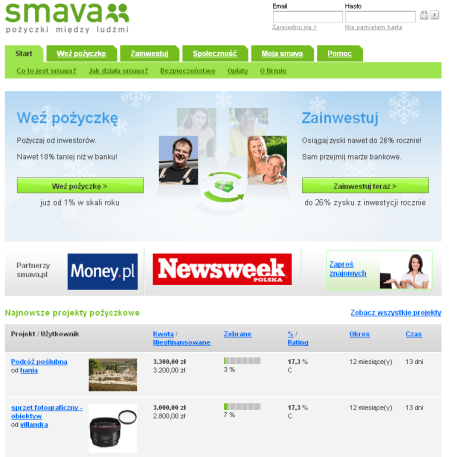
Following up on the interview (see ‘Smava expands p2p lending to Poland‘) I just took a look at Smava.pl, which has now launched. I don’t speak Polish but the layout of the site is very similar to the Smava Germany site, so navigation was no problem.

As expected interest rate levels in the Polish market are considerately higher then on Smava.de. At the moment there are 4 active listings with (nominal) interest rates ranging from 15.9 to 23.5% (maximum interest that can be entered in the application form for a loan is 26%). Loan terms are short. Borrowers can select from 3 months (minimum) to 36 months (maximum) with 9 possible durations.

Smava did keep the groups feature, which puzzles me  as groups have not gained any use on the German version in the nearly 2 years since launch.

One of the partners of Smava in Poland is Money.pl, a finance website with 2.6 million users per month. This is a good marketing move to gain visibility for the concept and to close up on the 3 competitors that launched earlier.

The management team consists of PrzemysÅ‚aw MoÅ›cicki, dr Marcin Klinowski and Arkadiusz Hajduk. Hajduk is a ‘veteran’ in p2p lending. He co-funded Fairrates (in Denmark) and later was product manager on the IOU central team (Canada).

Fynanz halts p2p lending

Prosper Lending Review examined how Fynanz, a p2p lending site for student loans,  quietly halted operations recently. In the article Tom points out that Fynanz attempts to market itself as a whitelabel service to credit unions and other financial institutions.

Fynanz CEO Chirag Chaman is cited that the reason for no longer accepting new lenders and borrowers are market conditions with sinking interest rates. Chaman outlines the plans to cooperate with financial intstitutions/banks to finance student loans.

Exclusive Interview: Smava expands p2p lending to Poland

Starting Jan. 7th, the German p2p lending service Smava will launch it’s p2p lending platform in Poland. I interviewed Smava CEO Alexander Artopé.

The following interview was originally conducted in German language. Possible translation errors are mine.

P2P-Blanking.com: Mr. Artopé, why has Smava chosen Poland as target market for the international expansion?

Smava: For several reasons. Poland is a fast growing economy with approx. 40 million residents. In Poland the span between deposit rate and base rate is very high – approx. 15 percent. Therefore the smava marketplace will be very attractive for polish customers right from the beginning. And regulation in Poland does not require a bank for the p2p lending model. This keeps transaction costs very low.

P2P-Banking.com: There are already 3 p2p lending services established in Poland. How does  Smava plan to win market share as newcomer?

Smava: Compared to the active services smava is much more secure. Like in Germany it is a central product feature, that the risk for the lenders is transparently evaluated and can be factored into the calculation . To achieve this we cooperate with the polish credit rating agency (BIK).

P2P-Banking.com: How did you organize the operations? Does Smava have a branch or a subsidiary in Poland? Or do you operate from Berlin?

Smava: We have a subsidiary in Wroclaw, Poland, with a polish management team.

P2P-Banking.com: Where are the biggest challenges in international expansion: technical, legal/regulatory, marketing or recruiting team members?

Smava: On all fields, in the following order: legal/regulatory, recruiting and then marketing.

P2P-Banking.com: Which differences does the polish version of Smava have compared to the german Smava version?

Smava: Firstly we will start in Poland without the ‘Anleger-Pools’ (P2P-Banking: an insurance feature), because p2p loans are mostly short term there. Secondly all loan contracts will be directly between lenders and borrowers  – not like in Germany with the biw bank as intermediary.

P2P-Banking.com: What will be the maximum loan amount that can be borrowed at Smava Poland?

Smava: A polish borrower can use smava.pl for loans up to 100,000 Zloty. Each lender can invest up to a maximum of 200,000 Zloty. (P2P-Banking.com: 100,000 Zloty equal approx.  34,000 US$)

P2P-Banking.com: Which credit rating information will Smava.pl supply for the lenders?

Smava: Like in Germany smava will supply a credit score (BIK) as well as a debt/income ratio.

P2P-Banking.com: Which fee structure does Smava.pl have?

Smava: Lenders can invest fee-free, borrowers pay 1%  of the loan amount. Continue reading →