My LendIt Europe 2015 Recap

LendIt Europe conference in London, where I have been the last three days, was a special highlight for me. The expertise and knowledge level of the attendees as well as the quality of the presentations is outstanding. The number of attendees jumped from from about 450 last year to more than 750 this year. And it was a chance for me to chat with representatives of many European p2p lending marketplaces.

Biggest news

  • Funding Circle acquires Zencap. Funding Circle buys German SME loan marketplace Zencap, which is active in Germany, Netherlands and Spain thereby expanding into continental Europe.
    I have done a separate blog post on this.
  • Insurance company Aegon will invest 150M Euro on Auxmoney
    Dutch insurance, pension and asset management Company Aegon will invest the amount in German consumer loans on the Auxmoney marketplace. This is a major move for both Auxmoney and the industry as it is the first big institutional investment coming form an insurer. It shows the industry has matured enough to attract capital from a clientele which is deemed rather conservative and long-term oriented in their investments.
Lendit 2015
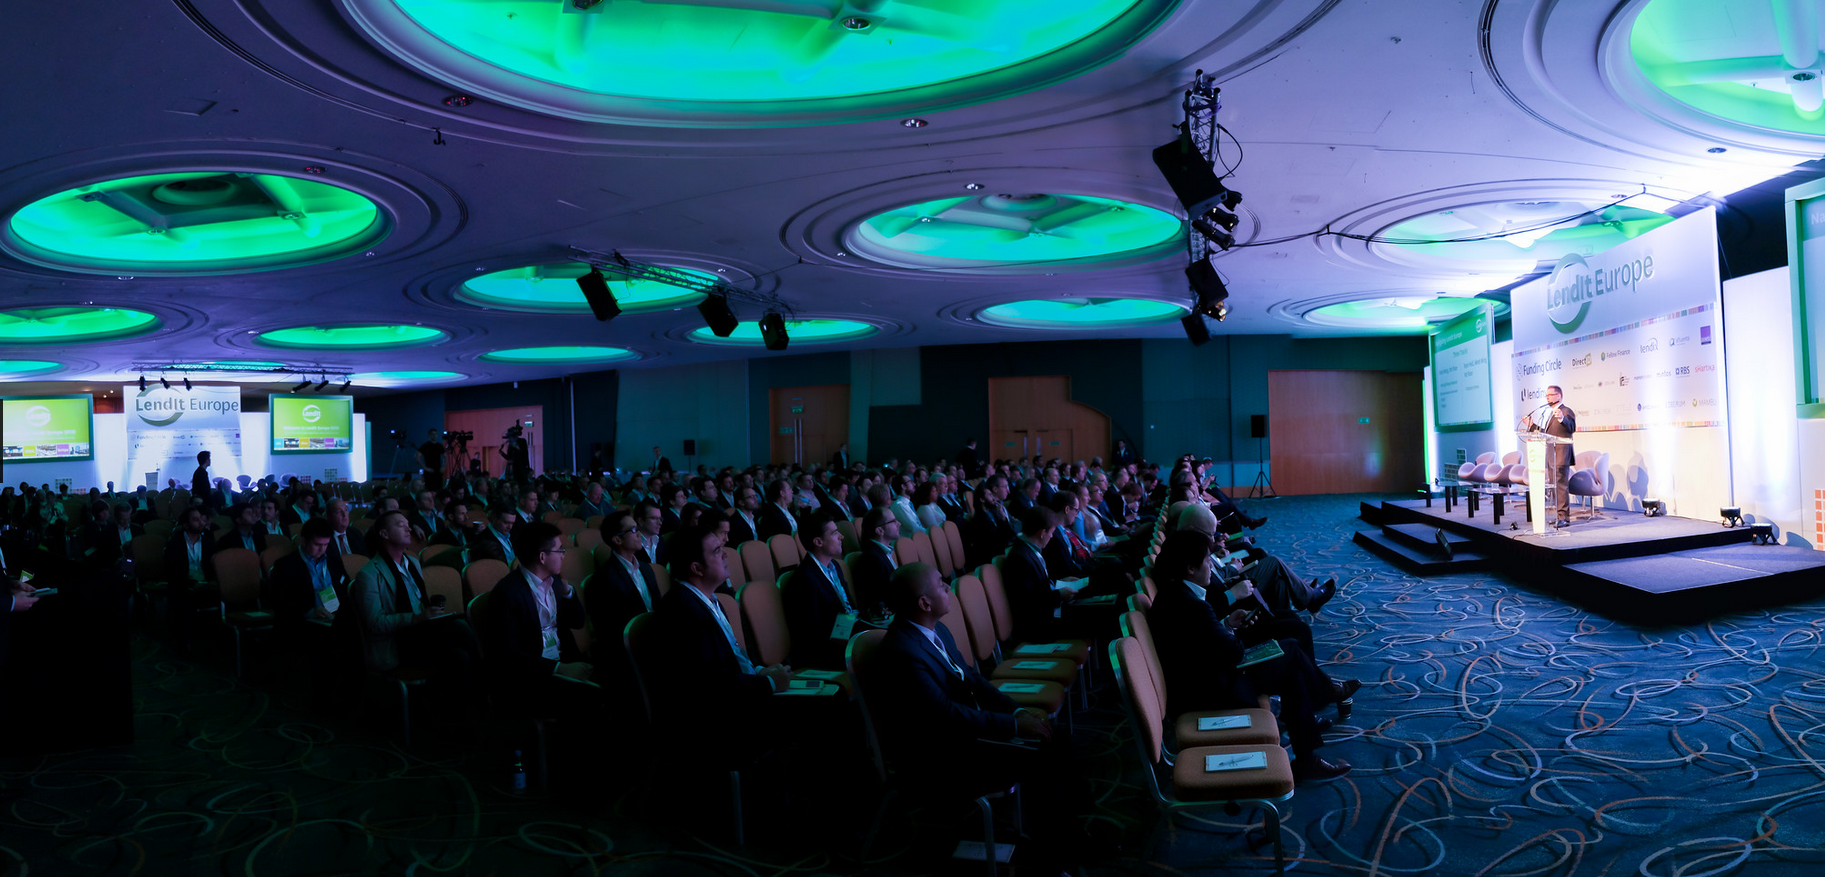
Peter Renton opening Lendit Europe conference (Source: Lendit Europe; photo used with permission)

Major trends

There are so many things evolving and it is sometimes hard to see which are the most relevant ones. And it certainly is a question of perspective. But from my view the three biggest developments are

1. Institutional investors will increasingly dominate the investor side

There is quite a consensus among most of the p2p lending marketplaces that institutional capital is very important for growing and scaling the marketplaces. While marketplaces value a mix of capital sources and many of them feel an obligation to retail lenders, which allowed the industry to create itself, the volume will be increasingly dominated by institutional investors. One way some platform see as a route to cater for a broader base of retail investors is to create funds that allow retail investor to buy into this asset class through traditional distribution channels. Still those platforms that are open to both kinds of investors pledge to guarantee equal access and not allow institutional lenders preferential access.
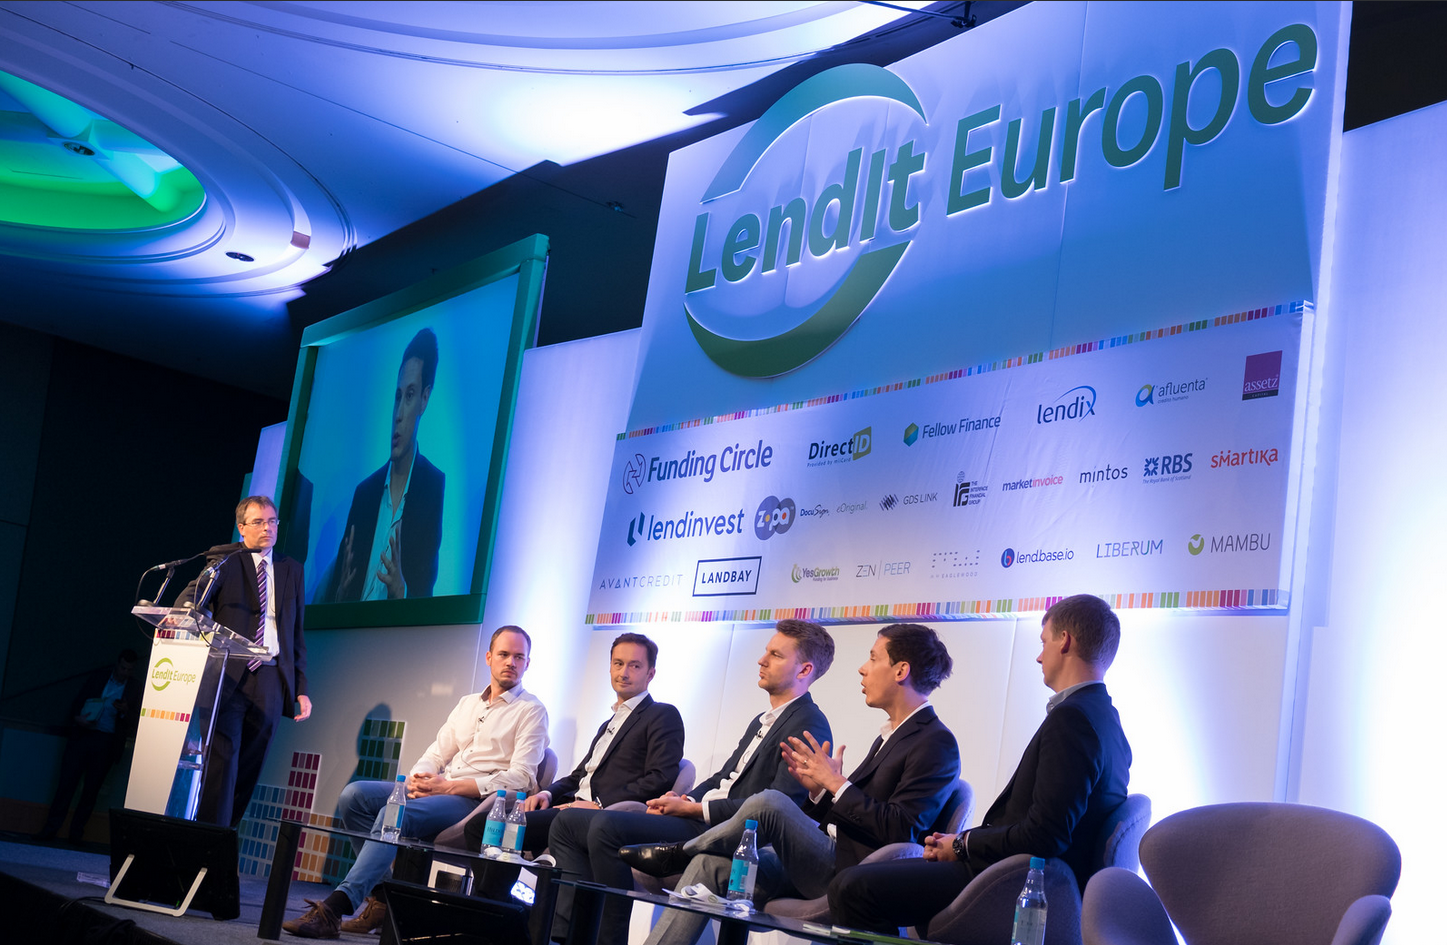
Lendit Europe 2015
The ‘Up and coming European platforms’ panel I moderated with panelists from Investly, Lendix, Mintos, Zencap and Fellow Finance (Source: Lendit Europe; photo used with permission)

2. Continued expansion in additional geographies

The headline news with the merger of Funding Circle and Zencap fits into the bigger picture as many platforms are moving beyond there national market. Examples include:

  • Matthias Knecht said that Funding Circle deems the Italian and French markets for SME loans as attractive targets for further expansion
  • Twino expanded into Polish loans
  • Lendix is considering expansion into Spain
  • Crosslend will soon open to Dutch loans and Dutch investors
  • Investly eyes expansion
  • Fellow Finance, which so far was available only to local Finnish investors launched an english language version of the site; expecting to attract retail investors from continental Europe
  • Pret d’Union expanded into Italy
  • Afluenta exanded into Peru and will expand into Mexico

On the other hand Aaron Vermut, CEO of Prosper, said at the dinner event ‘Global trends in consumer lending’ (thanks again for the invitation to that -it was very interesting) that Prosper has no plans to expand into other geographies, as that would distract Prosper too much and all activities are focused on the US market which offers a huge potential for further enormous growth.

3. The UK market offers a perfect environment for p2p lending companies

The UK market is a market were all puzzle pieces are falling into place and offer p2p lending marketplaces (and other alternative finance companies) an environment that has no parallels in any other country

  • The leading p2p lending marketplaces set up the P2PFA with represents about 90% market share (by volume) and was successful in getting heard when it came to new regulation
  • Regulation is specifically tailored considering aspects of p2p lending
  • The regulatory body FCA actually welcomes, if there are new entrants in the markets. In his speech Financial Conduct Authority Director of Strategy, Christopher Woolard, in essence said that the FCA thinks that the more new platforms are entering the market (providing they meet the minimum requirement) the better.
  • The government is highly supportive with new tax rules that allow offseting defaults against earned interests and investing into p2p lending through the new alternative ISAs
  • The British business bank is lending on multiple platforms for SME loans and open to consider more platforms, with the criteria for eligibility available on their website.

Given these preconditions analyst Cormac Leech is predicting that alternative finance companies might take away as much as 20-30% of bank’s consumer lending activity and more than 40% of banks SME lending activity over the next 10 years. Banks are still looking to find out what an appropriate startegy is to respond to that, and according to Matt Hammerstein of Barclay they’ll need to execute the strategy fast, once they defined it.

The debate on how this asset class will fare in the next recession is still ongoing. Continue reading →
New Twino CEO has Big Expansion Plans

Twino LogoOn October 1st Jevgenijs Kazanins became new CEO of Latvian p2p lending marketplace Twino. He previously worked as CMO at Estonian p2p lending marketplace Bondora. Twino was launched in June and is part of the Finabay group which operates since 2009. So far all loans offered on the p2p lending marketplace are from Latvia, whereas the Finabay group is active in a broader set of markets. Twino is open to international investors – German retail investors are the largest foreign investor base.

In a call with P2P-Banking.com the new CEO outlined the expansion plans. Twino will add loans from new markets, starting with polish loans shortly and possibly adding loans from countries like Russia, Denmark or Georgia at a later stage. There will be no currency risk for investors as it will be covered by Twino. Twino will apply its buyback guarantee to all loans – by which Twino covers overdue principal and interest for investors once a loan is 60 days overdue (though due to extensions this might take 8 month). The interest rate offered to investors for p2p loans in the new markets will be in line with the current offering: up to 14.9%. The loan terms will likely longer and Twino will move away from the current very short term loans many of which I deem essentially payday loans. He said: ‘… we are working on introduction of the loans from other markets, where Finabay has lending operations, such as Poland, Russia, Georgia and Denmark. The reason for the inclusion of other countries is that the demand from investors has already surpassed the volumes we can originate in Latvia. We aim to offer similar rates to the Latvia-originated loans and all loans will also come with the buyback guarantee‘

Jevgenijs Kazanins, TwinoSince the mother company Finabay is already originating these loans, it will not be a challenge to build loan volume. Kazanins aims to originate 5 million Euro loan volume per month. As the loans already exist and the new aspect consists only of refinancing through p2p investors, Kazanins is convinced of the good quality of the loans: ‘We estimate that 15-20% of [polish] loan volume will be bought back through the BuyBack Guarantee program (defaulted loans and loans with more than 6 extensions‘.

Twino also works to add statistics to the site. He stated: ‘ … Disclosing information about financial health of Finabay is highly important given the fact that all loans offered on the platform come with the buyback guarantee …‘

Loan extensions on Twino frequently prompt questions by investors. Kazanins has described in detail how loan extensions on Twino work here. Continue reading →

ING Partners with Equity Crowdfunding Site Seedrs to Tackle Belgium and Luxembourgh Markets

Seedrs logoING Bank partners with equity crowdfunding service Seedrs and reward based crowdfunding platform Kisskissbankbank to tackle the markets in Belgium and Luxembourg. Through this partnership, ambitious businesses will have a fast-track service for equity crowdfunding on Seedrs. The partnership will also raise the awareness of equity crowdfunding in the wider business community.

During consultations with businesses, ING Belgium representatives will assess which platform may be suitable and discuss how it works. Using the ING fast track procedure it only takes the entrepreneur a couple of clicks to submit an initial campaign enquiry for review. When Seedrs receives a project through this new route, it will be assessed within two days to determine if it’d be a good fit for Seedrs and equity crowdfunding. Continue reading →

Breaking News: Trustbuddy Suspends Operations – Investigations on Misconduct

UPDATE Oct., 19th: Trustbuddy has filed for bankruptcy

An investigation initiated by the new management of TrustBuddy AB has indicated serious misconduct within the company. The Board of Directors has informed Nasdaq OMX and the Swedish FSA about the situation, and the FSA has demanded that TrustBuddy is to stop offering its services with immediate effect. As a consequence, the company’s planned rights issue is suspended. The Board of Directors will prepare a control balance sheet and are currently evaluating all available options in order to find a viable solution for all parties.

Background

The new management team has been in place since early September, 2015. In connection with the repositioning of the business, an investigation of the business activities undertaken by the former management was initiated. The investigation is ongoing, but has so far pointed at several breaches of internal or external regulation:

  • The Company has used lenders’ capital in violation of their instructions, or, without their permission. As a result, there is currently a 44M SEK (approx 4.7M EUR) discrepancy between the amount owed to lenders and the available balance of the client bank accounts.
  • The total amount currently lent out on the platform is approximately 300 MSEK, of which, 37 MSEK is not assigned to lenders.
  • The Company has re-assigned existing loans, a significant portion of which were likely non-performing, to new capital deployed by lenders.

The investigation indicates that these practices were likely in place since the TrustBuddy platform began operation.
Actions taken by the new management and the Board of Directors

The questionable practices mentioned above, limited to the Company’s short-term lending business, have been stopped with immediate effect.

Further, the Board of Directors informed Nasdaq OMX and the Swedish FSA about the findings. Based on the findings, the FSA demanded that TrustBuddy is to stop offering its services with immediate effect. As a consequence, the planned rights issue, scheduled to run from 14 October 2015 to 30 October 2015, is suspended.

Due to the severe breaches of the internal and/or external regulation, the Board of Directors has also decided to file a report to the Swedish Police Authority.

The Dutch subsidiary Geldvoorelkaar, which focuses on lending to small and medium-sized enterprises, has been operating on a stand-alone basis and has not been subject to misconduct. Continue reading →

Rumour: Is Funding Circle Buying Zencap?

There is an article in a German startup news magazine speculating that Funding Circle might have bought German p2p lending marketplace for SME loans Zencap from Rocket Internet or is in the process of doing so. The article does not provide any evidence but cites unnamed entrepreneural sources.

I reached out to both Funding Circle and Zencap for comment today but have not heard back yet. EDIT: I received a reply from Zencap that they do not comment on rumours/speculations.
I also checked the filing history of the commercial register and there have been no telltale filings on the Zencap file in the past months, therefore I doubt a sale has been completed. But it still is a possibility because it likely would take some time for the filing to appear.

While I don’t have any hard facts either, I think the scenario has some plausibility. In emails I exchanged with a Zencap founder in the past months, there have been hints about upcoming major developments (without any specifics) at Zencap. Also it would match the intentions of Funding Circle to move into continental Europe. Continue reading →

P2P Lending Marketplace Ratesetter Turns Five

Ratesetter LogoThis week UK p2p lending marketplace Ratesetter celebrates its 5th anniversary. When Ratesetter launched in 2010 it introduced the concept of a Provision Fund to p2p lending – an idea that has been adopted by several UK marketplaces since. The Provision Fund now stands at over £16m, the largest in the industry, and has ensured that so far no individual investor has ever lost a penny.

Since 2010, the fast-growing platform has delivered 815M GBP in loans to individuals, businesses and sole traders and expects to lend 500M GBP this year.  While most loans are used to buy a car (28%), to pay off more expensive credit card balances (18%) and for home improvements (17%), RateSetter’s 160,000 loans have funded things as diverse as a mobile pizza kitchen that operates from the back of a Land Rover, a didgeridoo and a wind turbine.

Over 26,000 people currently invest with RateSetter, a number that is growing.  In total, investors have earned 25M GBP in interest by using the platform. Continue reading →