Dutch Symbid will power the new platform Herofunding.eu. Herofunding is a new crowd funding platform of Idea Fabrik Plc., creators of the HeroEngine, an integrated platform for online game development and operation. The platform is scheduled to go live in in the beginning of April 2012 and solely concentrates on the video game industry. Interested game developers are already invited to sign up their projects. Once Herofunding is launched the crowd can directly invest in these game projects in exchange for an equity stake in the project. Hint: since Symbid users will also be able to invest, you can already sign up as an investor at Symbid, if you are interested to invest in game projects – then you won’t miss the launch. HEROFUNDING.eu uses a plug and play, white label crowd funding solution for video games developed by Gambitious.
Investments are possible for as little as 20 Euro. Both the investor and the developer (company) must be located in the EU.
Prosper.com announced today, that Prosper founder and CEO Chris Larsen moved from the role of CEO and Chairman to serve exclusively as Chairman. He will be replaced by Dawn Lepore, who previously served as CEO and chairman of Drugstore.com. Lepore will serve as interim CEO. Larsen said:
“As Prosper continues to achieve incredible growth, now is the time to embrace the next phase of the company’s evolution. As Chairman, I look forward to working closely with the executive team to build a truly innovative consumer credit company.”
Lepore led Drugstore.com from 2004 until its successful sale to Walgreens in 2011. During her tenure, Lepore repositioned the company to focus on over-the-counter, beauty, and vision business segments.
Prior to Drugstore.com, Lepore held positions at The Charles Schwab Company. In her 21-year tenure, Lepore played a key role in launching and building the firm’s highly successful e-commerce business. Lepore also served as Schwab’s CIO, a member of Schwab’s Executive Committee, and a trustee of Schwab Funds, among other executive roles.
Lepore currently serves on the board of eBay, Inc., and was appointed on Feb.23rd to Coupons.com Inc. board of directors.
This post reviews a selection of p2p lending companies and does a rating on more factors than just loan volume. While I describe below what factors led to my rating, please note that the rating represents my personal opinion.
The table lists the companies in alphabetical order and gives:
New loan volume per month
This amount is in all cases but Zopa retrieved from the company websites and represents loans funded from Feb. 16th till March 15th 2012, and then converted into US$ at today’s currency exchange rates.
Brand/Press
Extend and tone of press coverage in the past months. Since a large share of new users is introduced to p2p lending services via media, positive media coverage is extremely important. Continued positive media coverage has helped some companies to associate positive values to their brand.
Growth/Marketing
This column especially rates if the new loan volume is growing continuously month after month. Furthermore it puts the absolute volume into perspective to the size of the market. It is obvious that absolute numbers in a country with a small population (e.g. Estonia) will be much lower than those in a country with a large population (e.g. US). Furthermore it takes into account if the (online) marketing measures of the the company succeed in winning new borrowers and lenders (though in most markets lenders do not need to be actively acquired).
Sustainability
Sustainability rates a mix of several factors:
ROIs for lenders / default rates Most p2p lending companies that failed in the past, did so as a result of high default rates which led to negative lender ROIs and caused massive lender churn
Ability of company to raise new funding Most p2p lending companies still have to bridge a considerable time-span at their current growth rate before they become cash flow positive. The ability to raise more funding to finance continued operation is essential for their success. Isepankur announced that it operated profitable in 2011.
Business model
User satisfaction
This rates the publicly voiced user opinion. Major factor are the comments in forums. To a lesser degree I took the user experience published in blog articles into account. The problem with lender experiences published in blogs often is that the writer is casting a positive image, since he earns commissions for newly referred customers through the affiliate program of the p2p lending site. Also these review are often written at the start of the lending activity at which point the lender’s ROI is naturally unharmed by the experience of defaults.
*estimate Empty fields: I had not enough information to rate these. E.g. with some of the new UK p2p lending companies I felt I had too few indicators to reach an opinion.
Availability of information also influenced the selection of companies. Due to language barriers including more services (e.g. the Japanese p2p lending companies) was not feasible for me.
Developments since last year
UK and US markets show impressive growth. A few smaller players stopped funding new p2p loans (Quakle, CommunityLend, BigCarrots). German services are struggling to achieve growth (Auxmoney had 2 good months lately).
British P2P Lending marketplace Zopa celebrated its 7th birthday today. Zopa was the first to initiate a p2p lending marketplace over the internet, an innovation that meanwhile has grown to an industry with dozens of p2p lending services launched operating in most G20 economies.
Giles Andrews, cofounder and CEO of Zopa said, ‘After 7 years, Zopa members continue to enjoy better rates on personal loans and savings than the banks offer. Meanwhile, despite their size and virtual monopoly, banks have struggled to even stay solvent, requiring huge taxpayer bailouts.’
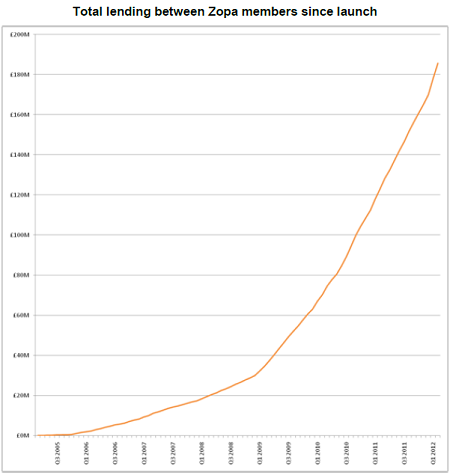
Since launch, Zopa has arranged more than 185 million GBP (approx. 291M US$) in loans. As older loans have been repaid, an estimated 90M is currently still loaned out. According to company statements Zopa loans now account for between 1% and 2% of all new personal loans issued in the UK each month. In January Zopa arranged more than 8.2 million GBP of loans.
Ratesetter yesterday added more choices. Borrowers can select loan terms of up to 5 years. Lenders can invest money for 1 or 5 years (in addition to the existing monthly access and 3 year term choices). It is interesting that Ratesetter has decoupled the borrower’s products from the lender’s products. For a borrower loan with an 18 month term there is no directly matching lender product. Ratesetter will combine funds invested in monthly access with money invested in 1 year bonds to fund these loans.
Bottom line of this, as I see it, is that Ratesetter will steer towards more active management of the money invested. Unlike other p2p lending marketplaces that act more like a platform, but where the users alone make the investment decisions, Ratesetter will directly take action.
Today Canadian p2p lending site Communitylend announced that it will close the p2p lending marketplace to focus on its consumer lending business. Communitylend will continue to service existing loans; there will just be no new ones.
Quote from the announcement:
If you have been following the CommunityLend Peer to Peer (P2P) Lending story over the years you might have been wondering why we have been so quiet here here recently. Â The short answer is that we have been trying to decide how much more time to spend on our P2P Lending site in light of a larger and faster growing consumer lending business we also operate called Financeitâ„¢.
We have now made the decision that we will be suspending the operations of our P2P lending site so that our team can focus solely on Financeitâ„¢.
This has not been an easy decision for us but one which has come about over time because of our observation that P2P Lending, as it needs to operate within the Canadian regulatory system today, has enough headwinds blowing against it that getting to a significant scale was going to be both expensive and difficult.   As we searched for solutions to these challenges as a P2P Lending operator, we kept our focus on our desired goal, to create a lending product for Canadians that gave them a less expensive and more convenient way to get an instalment loan.
We realized that we needed to get closer to where the borrowing “transactionâ€â€™ occurred instead of recruiting the borrower after the fact.  People buy things in a store location (offline and online) and too often just use their credit cards and then carry balances with high interest rates. We realized that helping people at this transaction moment was the key to driving interest in our lending product. This conclusion led us quickly to focus on sales finance and starting in late 2010 we launched a market leading sales finance platform called Financeitâ„¢. Continue reading →