Investing on the Mintos Secondary Market – Hint 2 – Buying overdue loans at discount

On the p2p lending marketplace Mintos there is a very large and active secondary market. In my previous article I described that the YTM calculation shown on the secondary market is based on the assumption that the buyer holds the loan part till regular end of term and the buyer will achieve a higher yield, if he buys at discount and the loan is repaid prematurily.

In the article I will look into a possible strategy on the Mintos secondary market: buying overdue loans at discount.

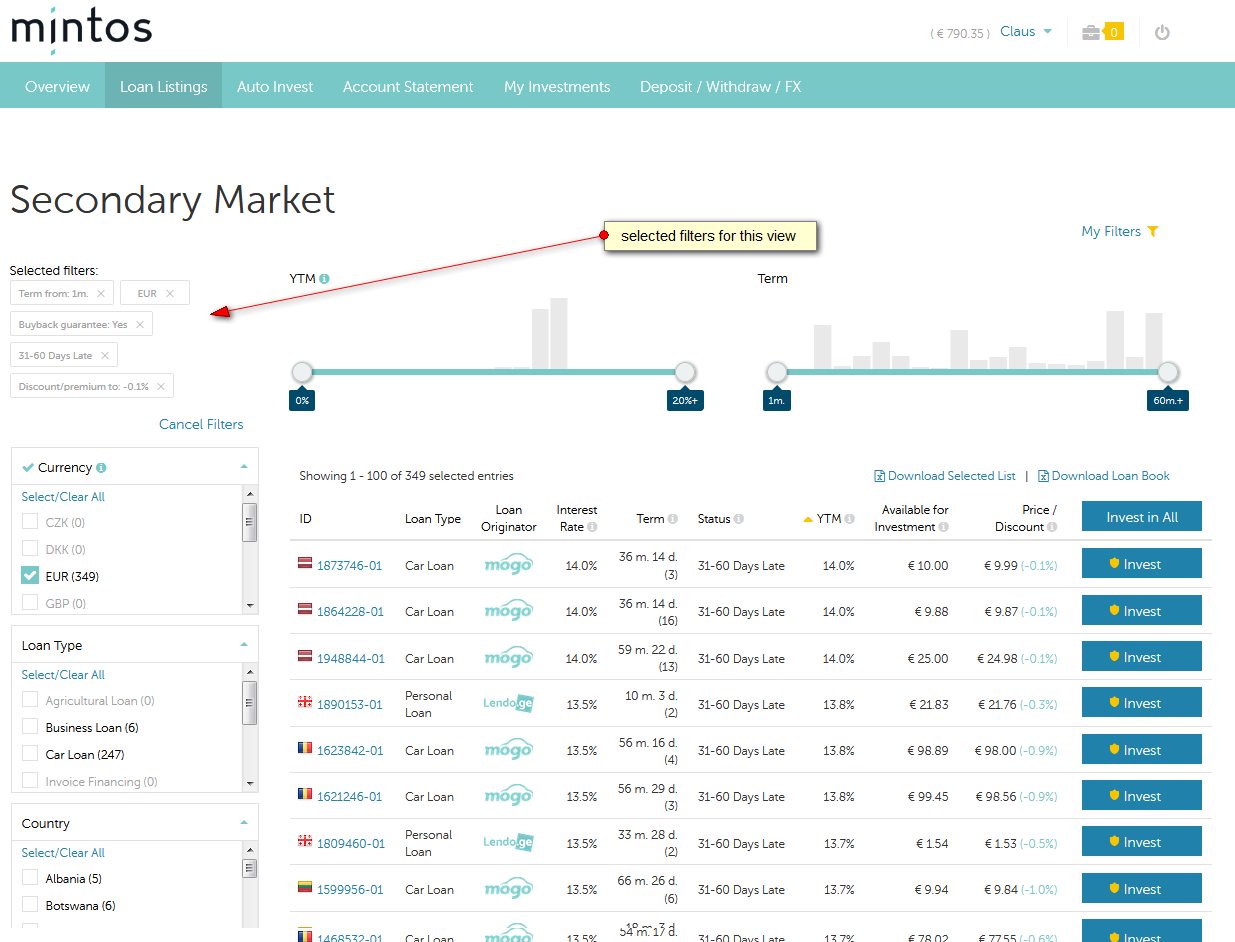
In a first step I sort/filter the buyback loans to only have those at discount that are very late (31-60 days overdue).
Mintos Screenshot
Click on image for larger view

I get a result of 349 loans with various discounts and an YTM of up to 14%. Not surprising for me, many of the loans listed at the top are Mogo loans. These are less attractive for buyers with this strategy. Why? Because they actually have a lower probability of defaulting. The paradox of this strategy is that the buying investor actually wants a high probability that the loans he buys default because that will boost his yield.

So in the next step I sort/filter to exclude Mogo loans. I also exclude loans that have a low YTM. This, because there is a chance that they do payup and then the buyer might be stuck with the loans for longer than 30 days.

Mintos Secondary Market
Click for larger view

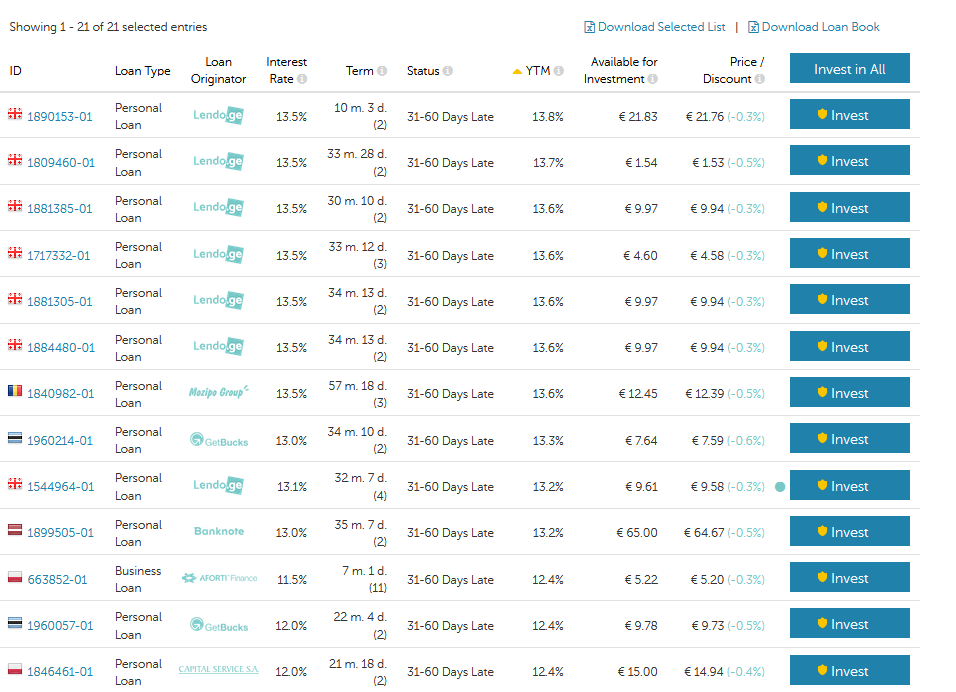
Finally let’s change the filter to require a minimum discount of 0.3% and there are 21 results:
Mintos Secondary Market Strategy
Click for larger image

What would a buyer get?

If these loans do pay up and then run till regular maturity date, then he recieves a yield of 12.4% to 13.8%. Decent, but not very high compared to other Mintos loans.

However there is a chance of at least 50% that these loans will default and are bought back within the next 30 days. If that happens to a loan, that a buyer bought at 0.3% discount, it will boost his yield very roughly by more 3.6% (0.3% for 30 days multiplied by 12 to get annual effect). Likely it is more because the next payment date will be less than 30 days away. But even taking 3.6% the yield will be around 17%.

Looking at it, it is obvious that discounts as high as possible are preferable. The loan with the 0.6% discount would mean a boost of very rougly 7.2% yield on top (0.6*12). So that could lead to about 20% yield.

I have taken the screenshots for this article just at a random point in time. Higher discounts do happen and discounts of around 1% are not a rarity.

This is certainly not a strategy for a beginner at Mintos and it requires time and monitoring, but it is a frequently used strategy when investing on the Mintos secondary market.

Not yet investing on Mintos? Get cashback!

Mintos is offering 1% cashback on all investments made in the first 90 days after registration if you use this link to signup: Mintos registration. Currently there is an additional cashback offer for new and existing investors of 4-5% cashback on Mogo loans with loan durations of 48 month or more. Need to enroll once (click banner in dashboard after you finished registration). Expires Feb. 16th. The 4-5% roughly equals 1% increased yield.

More cashback offers are listed on the P2P-Banking p2p lending cashback list.
 

Investing on the Mintos Secondary Market – Hint One

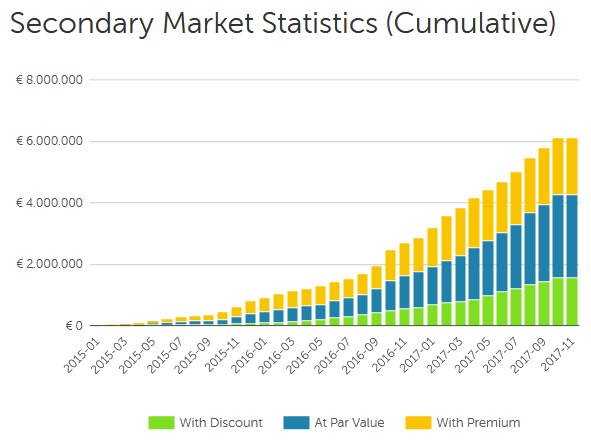
On the Mintos p2p lending marketplace the majority of investors invest on the primary market into loans, either manually or via autoinvest. But for the 29% of investors that do invest on the secondary market picking loans presents them with a huge choice of about 125,000 offers (no typo, really 125K loan parts on offer!).

Main characteristics of the Mintos secondary market:

  • no transaction fees
  • selling at discount, par or premium, adjustable in 0.1% increments
  • no minimum amount for buying, a buyer could make a partial buy of 0.01
  • seller and buyer each get credited interest for the amount of days they hold the loan; that means seller continues to accrue interest for an offered loan until the part is sold
  • good filtering

Sorting on the secondary market is preset to YTM (yield to maturity). This figure shows the yield the buyer would make (taking into account the discount or premium), if he would buy the loan and hold it to regular (!) maturity. Emphasizing regular is important since many of the buyback loans end prematurily, which would result in a higher than shown yield for loans listed at discount or lower than shown yield for loans offered at premium.

Generally YTM is a very good criterion for sorting an filtering on Mintos the secondary market and it is my most important criterion.

However there are exceptions, when taking the shown YTM at face value is not advisable.

Mintos secondary market
Click on image for larger view

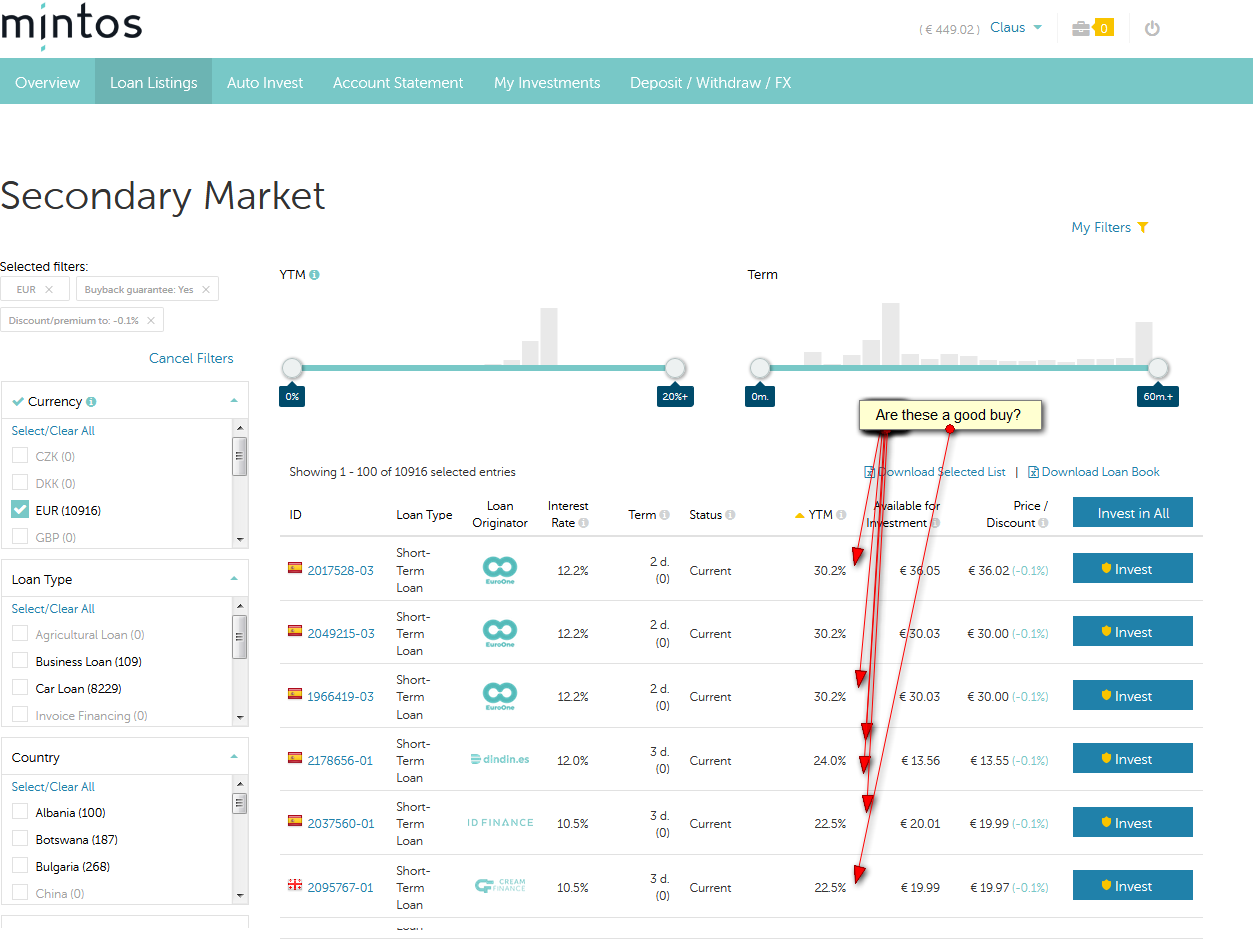
Look on the loan offers in the screenshot above. All are offered at 0.1% discount and the YTM is very high with 22.5% to 30.2% Let’s neglect for the moment that picking these loans would cost the seller time, which if he puts a price tag on time spent would not be worthwhile as these loans are very close to maturity and he would only earn interest for a few days.

The high YTM is caused by the discount in combination with the fact that there are only 2 or 3 days left to regular end date of loan (term is 2d or 3d). The calculation is correct, but there is one caveat. For the shown loans there is a very high probability that they will miss the payment and therefore run an additional 60 days until they are repaid under the buyback guarantee. If that happens the remaining actual loan duration would be 62 or 63 days and the impact of the 0.1% discount on the YTM would be much smaller. The resulting YTM would be somewhere around 11 to 13%. So they would not be a good buy and there are much better offers on the secondary market.

Another example to look at:

Mintos secondary market
Click on image for larger view

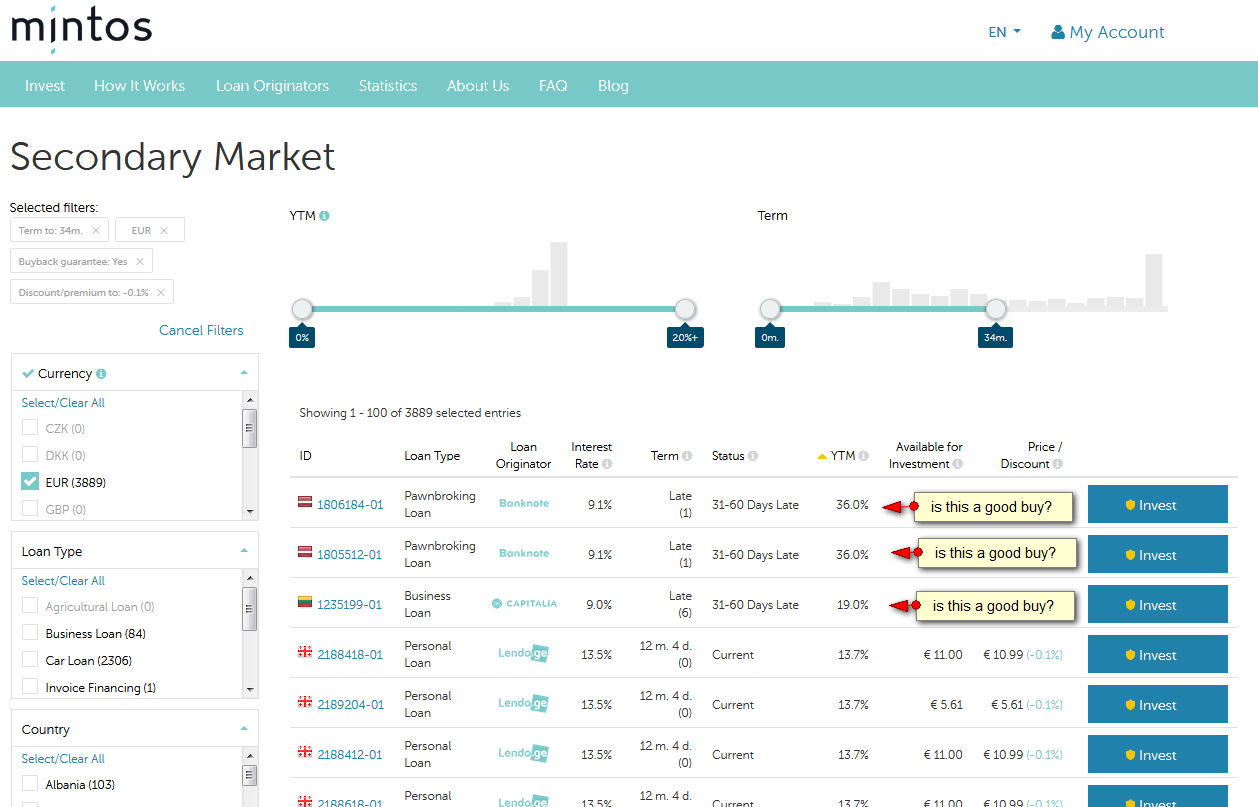
These loans are shown with an even higher YTM of 36% and offered at a discount of 0.1%. They are late, but with a buyback guarantee, so aside from the originator risk there is no default loss risk. But for these late loans Mintos calculates the duration to the regular end of maturity with only one day, which in combination with the 0.1% discount results in the high YTM (simplified: 0.1% per days * 360 days results in 36% yield)

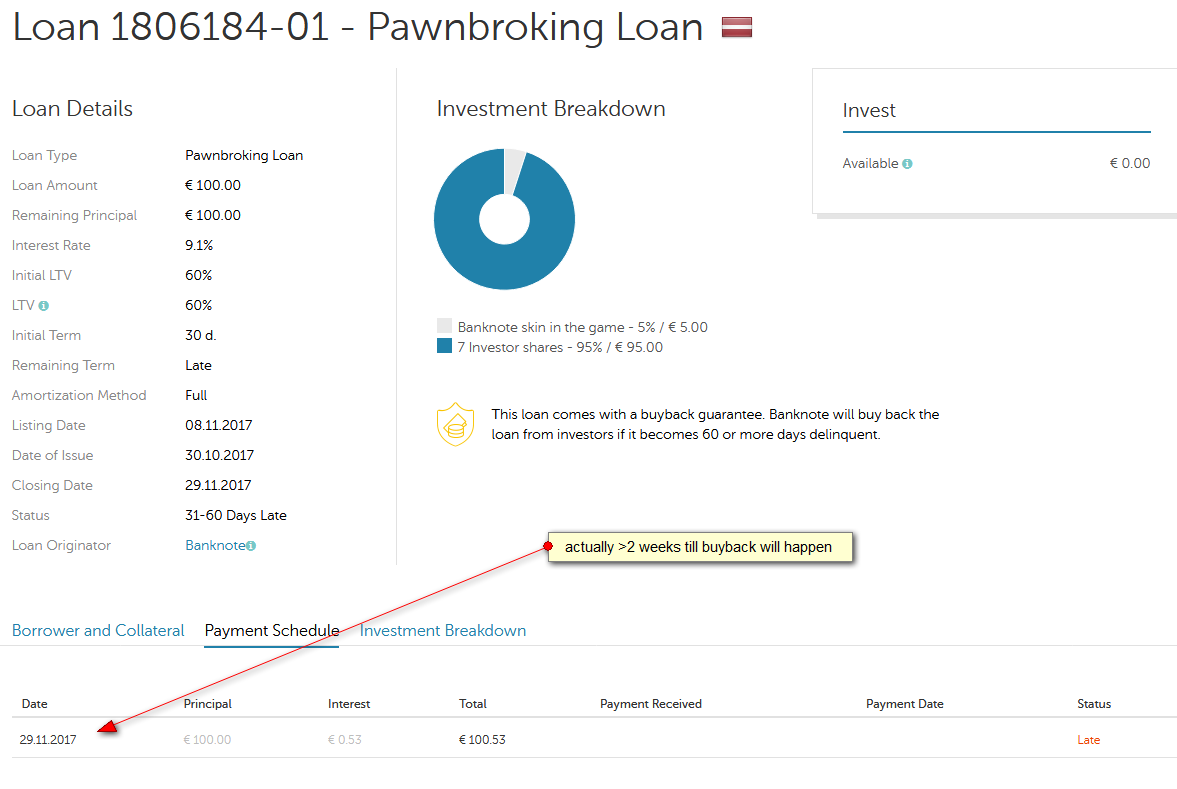
If I look into the details of one of these loans, I see that the next payment is actually scheduled in two weeks. So the loan will be repaid then since it is already in the status of 31-60 days late (there is a very low probability that it will repay earlier if the borrower repays).


Mintos secondary market
Click on image for larger view

With two weeks remaining the effective YTM for a buyer is not 36% but rather around 12%. Again there are offers with better YTMs on the secondary market.

Conclusion

On the Mintos secondary market YTM is an important figure to regard for buyers. However, while it is calculated correctly under the definition, there are a few cases where the shown figure alone might be misleading especially in case of loans that have less than 1 month remaining loan duration. The shown YTM always applies to the case that the buyer would hold to the loan to the regular maturity date.

Not yet investing on Mintos? Get cashback.

Mintos is offering 1% cashback on all investments made in the first 90 days after registration if you use this link to signup: Mintos registration. Currently there is an additional cashback offer for new and existing investors of 4-5% cashback on Mogo loans with loan durations of 48 month or more. Need to enroll once (click banner in dashboard after you finished registration). Expires Feb. 16th. The 4-5% roughly equals 1% increased yield.

More cashback offers are listed on the P2P-Banking p2p lending cashback list.
 

Up to 5% Cashback On Long-Term Investments Offered by Mintos

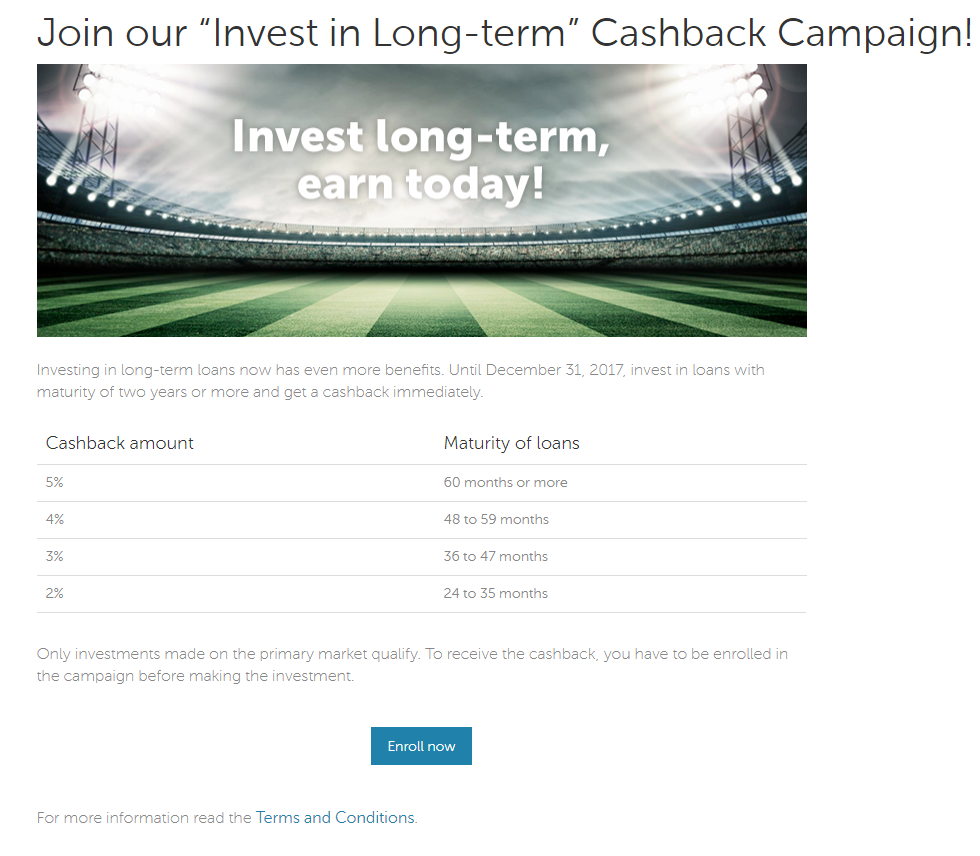
Lativan p2p lending marketplace Mintos just launched a cashback campaign running for the remainder of December. Investors investing in new loans with a term of at least 24 months on the primary market will receive a cashback of 2% to 5% depending on term length. The cashback will be credited within 6 days says Mintos.

This is a big bonus that goes on top of the 12 to 14% interest rate that these longer term loans at Mintos typically carry.

Important: To be eligable an investor needs to enroll once for the campaign by clicking on the promotion banner inside the Mintos dashboard.

New investors can even get an additional 1% cashback on all investments made within the first 90 days of registration (credited monthly) by registering via this link,

Most loans on Mintos are in EUR currency, but other currencies are available, too. Only recently Mintos started listing loans in GBP currency too.

See the P2P Banking cashback page for more cashback offers.

mintos cashback

“Investing long-term has many benefits. Loans with a maturity of two years and more on average have higher interest rates. As the maturity of these loans is longer, these higher rates can be locked-in for longer as well, thus avoiding cash drag effect. Also, investing in long-term loans allows for a better diversification, because this way investors can access types of loans and borrowers that have a different profile than the average short-term loan takers. We hope that in combination with our cashback campaign, all of these benefits will help our investors reach their investment goals in a more efficient and rewarding way,” says Martins Sulte, CEO and co-founder of Mintos.

Mintos Scraps Secondary Market Fees

Latvian p2p lending marketplace Mintos announced today that all transactions on the secondary market are now free.

Exciting news! Starting from today, November 1, 2017, we have removed the 1% fee for selling loans on the secondary market of the Mintos marketplace. This means from now on, there are absolutely no fees for investing through Mintos.

“A secondary market with no fee will greatly benefit our investors. We expect the secondary market to become even more liquid now. This is especially good news for investors who want to pursue a long-term investment strategy and invest in loans with longer maturity. In the case investors will need the liquidity before the loan matures, they will be able to sell their investment with no extra fee added,” says Martins Sulte, CEO and co-founder of Mintos.

The monthly volume of traded loans on the secondary market is about 300,000 Euro per month.

Mintos secondary market

Baltic Bondora stopped charging fees on its secondary market in November 2015.

Mintos Reaches 50M Loan Volume Milestone

Mintos logoP2P lending marketplace Mintos crossed 50 million Euro in loans to both private individuals, as well as small and medium sized businesses after 18 months of operations. Mintos marketplace arranges loans from 14 non-bank lenders, which have joined the marketplace from the Czech Republic, Estonia, Latvia, Lithuania, and Poland.

According to funded loan volume, to date most money has flowed into loans in Latvia’s – 33%, Lithuania’s – 31% and Estonia’s – 23%.

‘All around the world, peer-to-peer lending concept is slowly replacing bank services from which the commercial banking sector is retreating. Today, banks no longer conduct the main mission of the financial system — connecting those postponing consumption with those who are consuming today, i.e. connecting savers and borrowers. Deposit rates are close to zero or even negative, while access to credit is limited. This increases the non-bank financial services market, which offers consumers easy, convenient and affordable services,’ emphasizes Mintos CEO and co-founder Martins Sulte, predicting that by year end, investors through Mintos will have financed EUR 100 million in loans. Continue reading

Mintos Raises 2M from Skillion Ventures

Mintos LogoLatvian p2p lending marketplace Mintos has raised 2M EUR from VC Skillion Ventures in Riga. The p2p lending service was launched a year ago and lists loans from several loan originators. The loan types include mortgage loans, secured car loans, business loans, personal loans and invoices finance. The majority of the retail investors resides in Latvia, Germany and UK.The investors financed a cumulative loan volume of over 16M EUR since launch.

The loans are currently to borrowers in Latvia, Estonia, Lithuania and Georgia. Mintos CEO Martins Sulte plans to add loans in the markets of the Czech Republic and Poland next. Continue reading