Interview with Gideon Valkin, CEO of FriendlyScore

What is FriendlyScore about?

FriendlyScore is about allowing borrowers to use their online footprint as a way of increasing the amount of information a lender has about them. This can be useful for borrowers who lack credit history to get access to products they deserve, and also for allowing borrowers with some history to get better products by making lenders more comfortable with their risk profile.

How can your company help p2p lending marketplaces? Can you please share some references?

We help lending marketplaces make better credit decisions by enabling them to get way more data on their customers. By incorporating FriendlyScore into the platform’s decision engine, we can help prevent outright fraud; validate user identity and personal information; and most importantly, gain propensity insights from the users behaviour. This allows the platform to approve more borrowers (or lenders), reject more fraudsters and bad borrowers, as well as price their risk more accurately.
Gideon ValkinA borrower your software identifies as creditworthy has been previously ruled out by the scoring mechanism of the marketplaces. How would the marketplace deal with this loan when showing a credit grade/score class for this loan to investors? Assign a new class?

Our most common use case in the p2p space is for FriendlyScore to be offered as an optional way for borrowers to bump up to a higher internal credit rating if they get a high FriendlyScore. In other words, it is an opportunity for borderline declines to get bumped up to higher-riskaccepted, and for the accepted applications to get a better risk grade and hence a lower interest rate from the lending community. This allows the marketplace to increase approvals and hence conversion and also to more competitively price good borrowers. As our algorithm develops, we expect to be able to function as a standalone credit score.

How do you price your service for p2p lending marketplaces?

Our standard pricing is on our website at https://friendlyscore.com/page/pricing. We charge a subscription price to make the decision simple and easy for marketplaces. We are open to alternative, variable pricing models where they make more sense for the customer on a case-by-case basis.

Do you think your service will be more beneficial for marketplaces in developed countries or in developing markets or what factors indicate in which markets you could add most value?

We can service marketplaces in any market because, at the core, we are simply a data enrichment and machine learning platform for improved decisioning. We are however seeing steadily increasing interest from emerging market lenders which makes sense based on the following two macro factors that drives demand of our product:

1) Shortages of credit bureau data (much more prevalent in emerging markets). 2) High internet and social media penetration (much higher in developed markets but converging quickly). We will always be able to help developed market lenders access non-traditional borrowers (students, young professionals and foreign nationals). However, in developing markets where vast portions of the population lack financial history, and will soon be using the internet as much as anywhere else, we have a chance at bridging an accessibility gap in finance that unfairly applies to a large portion of the normal population. Continue reading →

Fellow Finance Expands to Poland

P2P lending marketplace Fellow Finance is now open for borrowers in Poland. Polish customers can now apply for peer-to-peer loans with maturity from 1 to 3 years up to 12 000 PLN. For Fellow Finance investors this gives an opportunity to diversify their investments geographically and in two currencies (EUR and PLN) with single consolidated user interface and reporting in investor’s own preferred currency. The ability to operate in multiple currencies also enables Fellow Finance to scale its platform to new geographies swiftly in the future.

‘Poland is a huge market in Europe with 38 million people. The Polish economy is one of the fastest growing in Europe. Consumer and consumption behavior are changing with the expanding economy. Mobile penetration and online lending have seen a fast and continuous growth in the last 4 years. Launching operations in Poland makes Fellow Finance a genuine international platform where investors can easily do direct investments in consumer loans across geographies and in multiple currencies. …’ says Jouni Hintikka, CEO of Fellow Finance. Continue reading →

Marketplaces Step Up Incentives for Investors

Currently there is an increase of promotions by p2p lending marketplaces in order to acquire and activate retail investors. Cashback offers are more frequent and Funding Circle is giving away iPads to investors that will invest at least 20,000 GBP during the Funding Circle spring promotion. Investors welcome these added benefits, but for marketplaces it is a fine line to walk. They want to grow originations, but risk that investors will expect getting extras and might hold back further investments until the next offer is made.

Funding Circle Spring Promotion
(Image source: Funding Circle)

Google Advertising Lending Club Loans

I have written about the partnership between Google and Lending Club earlier. The image below shows an actual advertising message Google is sending to its Adwords customers. Note that a special loan is offered, not a standard Lending Club loan. This partnership is a great match for both Google and Lending Club. Google can enable its customers to get access to the funds they need to grow their business and potentially spend more on advertising services supplied by Google. Lending Club can target selected businesses, which were prescreened based on the data Google has via the Adwords customer relationship.

google-lendingclub
Image source: Business2community.com


International P2P Lending Statistics – March 2016

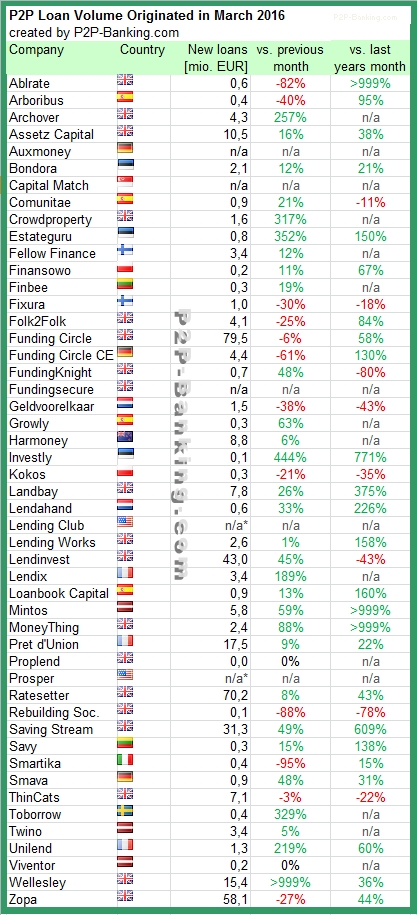
The following table lists the loan originations of p2p lending marketplaces in March. Funding Circle leads ahead of Ratesetter and Zopa. I added MoneyThing to the list. I track the development of p2p lending volumes for many markets. Since I already have most of the data on file I can publish statistics on the monthly loan originations for selected p2p lending platforms.
Investors living in markets with no or limited choice of local p2p lending services can check this list of marketplaces open to international investors. Investors can also check how to make use of current p2p lending cashback offers available.
Last month these companies crossed significant milestones:
P2P Lending Statistic 03/2016
Table: P2P Lending Volumes in March 2016. Source: own research
Note that volumes have been converted from local currency to Euro for the sake of comparison. Some figures are estimates/approximations.
*Prosper and Lending Club no longer publish origination data for the most recent month.
Notice to p2p lending services not listed: Continue reading →

How to Open a UK Bank Account Online

As I started to check the facts for this article I planned to title it ‘How to Open a Free UK Bank Account Online’. Lateron I had to omit the word ‘Free’ – see below, but it still is a bank account that anyone in Europe can open online, all that is needed is an Android smartphone. That’s right, it is not limited to British expats, but open to anyone living in Europe. There is no iPhone App yet, but it is planned.

Why I opened a UK bank account

For the UK p2p lending marketplaces I use as a non-UK resident, a bank account in the UK is not really necessary. I use Transferwise and Currencyfair to transfer money and handle the currency exchange. One process where I think having a UK bank account is very useful, is when I want to withdraw money from one UK p2p lending marketplace in order to then deposit it at another UK p2p lending marketplace. Naturally in that scenario, I do not want to convert the pounds back to Euro and I want the transfer to be fee-free.
Therefore I looked for a bank account, that would allow me to do this online. Another requirement was that I should be able to open this bank account without traveling to the UK and entering a bank branch.

I opened a Monese account

I opened a Monese current account. To do this, I first downloaded the Monese app on my Android phone. Then it took about 10 minutes to register. In the course of the process I took photos of the front and the backside of my ID, did a selfie (smile) and filled in a form. That part was completed rather fast.

After that I had an unverified account, which had some restrictions. To lift these I uploaded the PDF of a recent bill with my name and address on it and waited. It took about 6 days until my account was verified.

Benefits of a Monese account for me

I have an own bank account number. Together with the sort code (which actually is the one of NatWest since Monese cooperates with NatWest) I can transfer money inside the UK fast and free. This is the main function for me. The account has more features, but actually I won’t be using these. Should I want to transfer money from my Monese account to my Eurozone accounts I will continue to use Transferwise or Currencyfair instead of making the transfer as I currently think this is the best way to optimise forex rates and at the same time minimize transaction charges.

Is this a free account?

Monese accountWhen I signed up on March 18th, Monese promoted it as a free account. And in fact my account still is, I don’t pay a monthly fee and the transaction types I want to use are still free in my account (see screenshot). Other features – which I do not need like an ATM withdrawal or a card purchase abroad are priced.

But I talked to other investors, who signed up later than me (last week) and they were offered by Monese ‘First month free 4.95 GBP/ month‘. Seemingly Monese no longer offers accounts without a monthly charge to  new customers (if this is uncorrect and it is still possible to get open an account without monthly fees applied, please post hints and tips how to do it in the comments. Thx!).

It should be noted that the account is not covered by FSCS as it is regulated as an e-money product.

The app so far does what it should and is self-explanatory, if a bit basic.

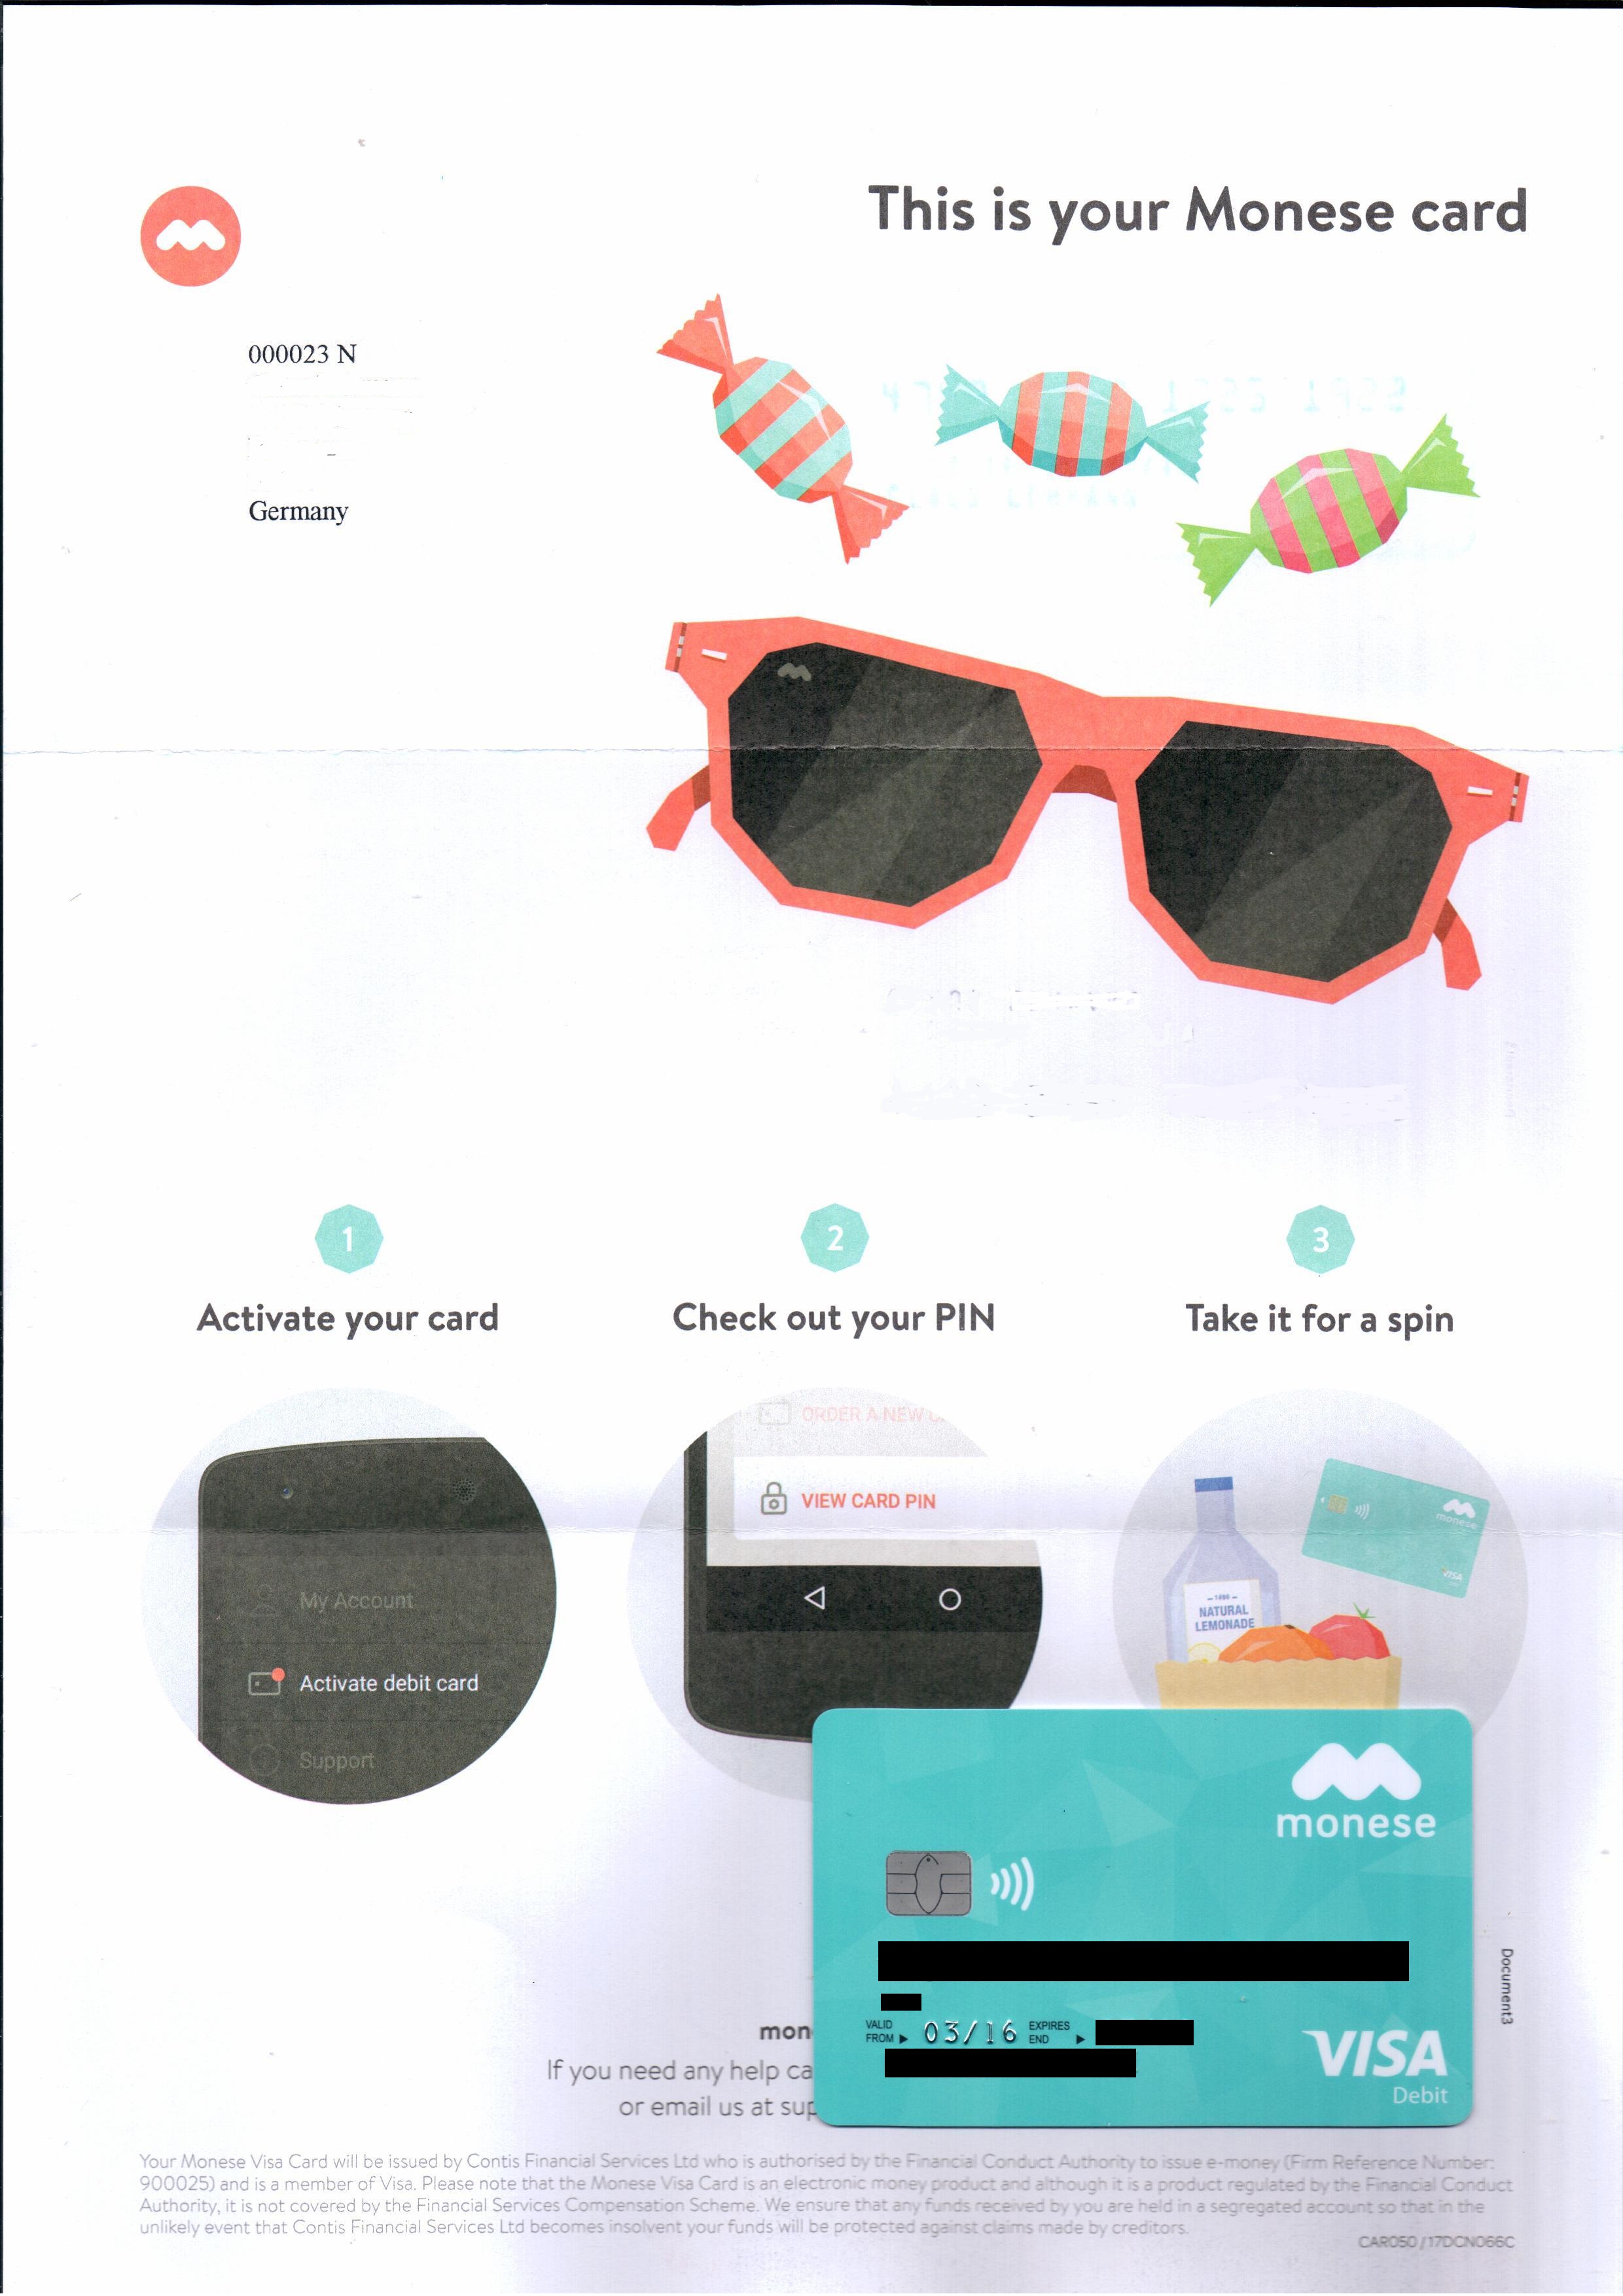
About a week after I opened the account I received a welcome letter with a VISA debit card, which I actually don’t need for my intented use of the account. But for other customers it will be useful to have a card with the account.

Monese VISA debit card

Update: Just received the message that my account won’t stay free either: ‘Hi …, as one of our early members you have been enjoying a mostly free service as part of our launch celebrations, only paying our rock bottom 0.5% fee on currency exchange when sending money abroad. Without you, we would not be here today and as a small “thank you” we’d like to give you an additional 2 months free servic. From 1st June, 2016 you will be billed a simpley fixed price of £4.95 per month taken directly from your Monese account balance,…’