I Opened a MoneyThing Account

Moneything logoTo achieve further diversification of my p2p lending investments I opened an account at the UK p2p lending marketplace MoneyThing. All loans on the platform are secured by assets, which consist of a mix of property and other items like cars. MoneyThing launched one year ago and has since originated 10 million GBP in secured loans. It is operated by Capital Mortgages Direct Ltd. in London. So far none of these loans had any troubles.

The key aspects for investors:

  • 12% interest rate p.a.
  • interest paid from the day the bid is made into a loan
  • no fees for investors
  • all loans secured by assets
  • bridge loans with a term of 3 to 24 months
  • there is a secondary market
  • minimum deposit is 100 GBP, minimum bid is 1 GBP

Steps to start lending

1. Registering

First I filled in the online form. MoneyThing is open to international investors, but the form had no country field, so I did enter town and country in the ‘town’ field. Later the same day I got an email from support asking me for ID and a further document to be uploaded as non-UK residents can not be automatically verified by their systems. I did that and within 5 minutes received the message that my account is now verified

2. Depositing

I used Transferwise to make my first deposit into the account to reduce transfer and currency exchange costs. A Transferwise alternative is Currencyfair. This time Transferwise took 3 days – a little longer than my usual experience for transfering to the UK with them.

3. Selecting the loans on the market

MoneyThing lists all loans in a single market view – there is no separate secondary market view. All available loan parts are highlighted in yellow. Since loans are sorted chronologically to find parts of older loans on sale the easiest way is to resort by the ‘Available’ column. Otherwise just scroll down.
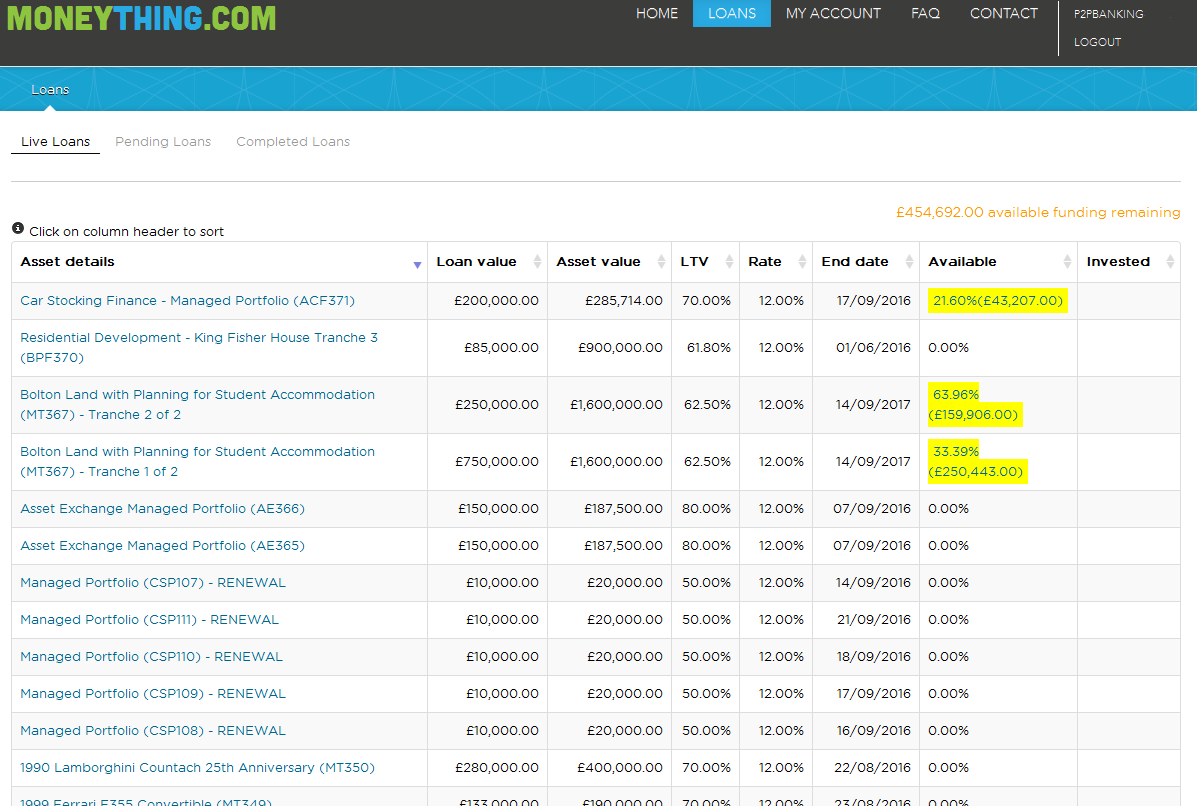
Moneything loan listings

Clicking on a loan reveals detail information about a loan and supporting documents (e.g. a valuation report). Continue reading →
Live Stream of the P2P lending Conference in Vilnius presented by Savy*

The first P2P lending platform in Lithuania, SAVY, is organizing their second annual P2P lending conference on the 23rd of March in Vilnius, Lithuania. Guest speakers from all over the world, including the co-founder of LendIt Conference Jason Jones and the leaders of the top Baltic P2P lending companies – Mintos, Bondora and SAVY, amongst others, will engage in a number of panel discussions and presentations.

The conference will be focused on the possibilities of P2P lending and Crowdfunding, while the participants will touch some important topics related to the prospects, challenges and trends for Alternative Financing on a global scale and in the Baltic region specifically, as it offers a considerably higher return on investments than most Western European countries.

https://www.youtube.com/watch?v=B29ozFU0CQE

Live stream of conference starting at 13:30 GMT+2 on March, 23rd

*Sponsored post: This post was paid for by Savy.lt, the conference organizer. I rarely publish sponsored posts, but in this case I thought the content is a very interesting fit for the blog audience.

P2P Lending Marketplace Afluenta Raises 8M Series B From IFC and Elevar Equity

Afluenta LogoAfluenta, headquarted in Buenos Aires, announced today the completion of its Series B funding round from the International Finance Corporation (IFC), the private sector institution of the World Bank Group, and Elevar Equity, a venture capital firm. IFC and Elevar Equity are investing 4 million US$ each.

Afluenta seeks to disrupt the traditional financial services industry, cutting out middlemen and using proprietary technology to transform the process of applying for a loan, thus facilitating access to financing. Afluenta says it offers borrowers a simple, affordable and less bureaucratic experience, while delivering better yield for individual and institutional lenders.

A pioneer in the region, Afluenta plans to use the proceeds of the Series B financing for accelerating its network expansion plan across Latin America. Launched in Argentina in 2012 and in Peru in 2015, Afluenta plans to launch new services in Mexico, Colombia and Brazil in the next 12 months to consolidate as the first pan-regional player of this new and disruptive alternative financing. Continue reading →

Twino to Remove Currency Risk for UK Investors

Latvian p2p lending marketplace Twino today announced plans to shield UK investors using the platform from currency risks. So far all investments on the platform are conducted in Euro. Twino already takes the currency risk of Polish Zloty, Danish Krone or Georgian Lari versus the Euro. Now it plans to make the platform more attractive for investors holding their assets in GBP. The announcement reads:

One of TWINO promises is that we protect investors from currency risk. Thus, while investing on TWINO you don’t need to worry about Polish Zloty, Danish Krone or Georgian Lari appreciating against euro, as every transaction on the platform is performed in EUR.

However, investors from the UK still face the risk of EUR appreciating against GBP, which might lower their returns. Therefore, next week we are planning to launch a major upgrade that will remove the currency risk for investors, who hold their investable assets in British Pounds, equalizing the benefits of investing on TWINO with Eurozone investors.

The functionality will allow investors to choose the currency that they want to invest in (either EUR or GBP), and every transaction on TWINO will be processed in the chosen currency (including deposits, withdrawals, investments, repayments, etc.).

We will provide a further notice when the new functionality launches, and will be reaching out to existing investors, asking if they want to convert their TWINO accounts to GBP.

We are glad to be the first platform in Continental Europe to provide such functionality and hope some of you will benefit from it!

The Twino CEO Jevgenijs Kazanins indicated that Twino is hedging the currency risk, an action that is possible for a platform with volume but not available or viable for individual retail investors, would they strive to do it on their own.

LendInvest Raises 17M GBP Series B from Atomico

Lendinvest logoLendInvest, a UK online marketplace for property finance, has completed a 17 million GBP (25 million US$) Series B equity investment from Atomico, the technology venture capital firm founded by Niklas Zennström, the co-founder of Skype.

This is LendInvest’s second equity investment in nine months. In June 2015, LendInvest secured a 22 million GBP (33 million US$) Series A investment from Beijing Kunlun, the listed Chinese technology company.

The round takes LendInvest’s total institutional funding (debt and equity) to over 200 million GBP (285 million US$).

LendInvest was launched in 2013 by founders Christian Faes and Ian Thomas, and has lent 560 million GBP to finance 2,100 properties in the UK. The UK mortgage market – a £1.3 trillion sector  is traditionally offline, slow and generally a very poor consumer experience says LendInvest.

Today LendInvest’s technology reduces the time taken to process mortgages from months to days, while maintaining rigorous credit controls. LendInvest has also opened up mortgages as a new and attractive asset class that delivers returns of over 5% per annum for investors.

LendInvest will use this funding to accelerate its investment in technology and extend its lead in the property finance market. The company is recruiting its first Senior VP of Engineering and will expand its technology and product teams. Continue reading →

Impressions from the P2P Investing Day in Prague

Today I am in Prague at the P2P Investing Day organized by Symfonie Capital. There are several Central and Eastern European marketplaces present like Bondora, Finbee, Estateguru, Zlty Melon, Symcredit and Zonky, but also Lendinvest and Ablrate from the UK. The content of the panels and presentations was not as basic as in last year’s conference. I’d estimate about 150-200 attendees.

One interesting discussion centered on the differences between a bank loan and a p2p loan for a SME loan borrower that has problems to make the payments. One argument was that the advantage of a p2p lending marketplace is that it can be more flexible in finding a solution, e.g. by prolonging the loan term – having power of attorney granted by investors it is free to find a solution it deems right for the situation. The counterargument was that the platform should adhere to a rather strict set of rules since it owes its investors predicitability. Personally I understand both views but as an investor I prefer platforms to stick to a predefined process, because only that will make collections and defaults rates predictable. If there is too much flexibility and on the spot decisions it will be very hard to statistically evaluate platform performance and development for troubled loans over time.

One interesting anecdote was mentioned by Lucie Tvaruzkova, CEO of Zonky, a consumer loan marketplace in the Czech Republic, launched several month ago. She said that at the moment there is a waiting list of 7,000 investors wanting to use the platform but to scale it properly in line with loan demand, she lets those in only bit by bit. So far 5,000 investors are already active on the platform.

Symvest 2016 p2p lending conference
Panel on consumer focused platforms with representatives of Savelend, Bondora, Finbee and moderator Michael Sonenshine

David Bradley-Ward, CEO of Ablrate, told me that he expects to put more airplane loans on the platform in 2016 than in the previous year, but has to be selective in which loans fit the investor appetite. He also says the situation gets easier as he now has institutional investment in place that can pick up loan parts that would otherwise go unfunded by institutional investors.

I liked the panel that had 3 SMEs, that borrowerd through a p2p loan, on stage, as this gave an interesting change of perspective. Continue reading →