The long announced IPO of marketplace lender Lending Club is imminent now, with the first day of trading expected to be around Dec. 10th.
Lending Club will issue 57.7 million new shares priced in the range of 10 to 12 US$. On the upper end this means the company will have a valuation of around 4.4 billion US$. At the same time existing shareholders will offer 7.7 million new share for sale. Lending Club did not forget it roots. At the begin of the astonishing growth curve it were the small retail investors that funded all the Lending Club loans. So now Lending Club has reserved 10% of the new shares and offered them to these retail investors through a ‘Directed Share Programs’ via Fidelity Investments. For each investor a certain amount of shares (mostly 350) was reserved and offered.
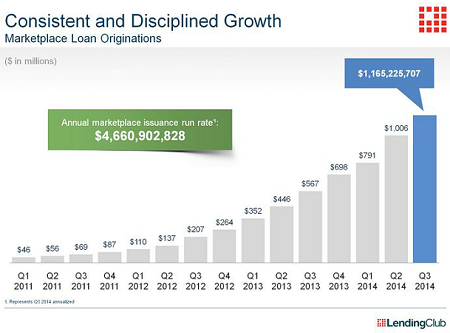
Aside from the IPO financials the big news is the strong position Lending Club has built in the p2p lending market:
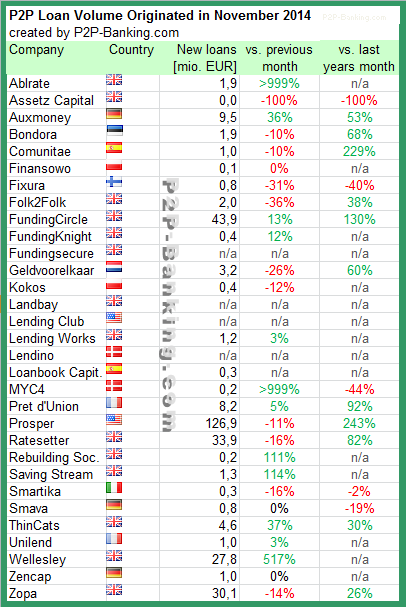
November was a month of mixed results for the listed p2p lending services. Some grew, some had a small decline in newly originated loan volume this month. Ratesetter crossed a total volume of 400 million GBP originated since inception. Ablrate profited from the deal with the first institutional investor, which boosted volume. I added one more service. I do monitor development of p2p lending figures for many markets. Since I already have most of the data on file I can publish statistics on the monthly loan originations for selected p2p lending services.
Table: P2P Lending Volumes in November 2014. Source: own research Note that volumes have been converted from local currency to Euro for the sake of comparison. Some figures are estimates/approximations.
Notice to p2p lending services not listed: If you want to be included in this chart in future, please email the following figures on the first working day of a month: total loan volume originated since inception, loan volume originated in previous month, number of loans originated in previous month, average nominal interest rate of loans originated in previous month.
For the coming Lending Club IPO a recent SEC filing reveals details on the valuation of the company.
LendingClub Corporation is offering 50,000,000 shares of its common stock and the selling stockholders are offering 7,700,000 shares of common stock. We will not receive any proceeds from the sale of shares by the selling stockholders. This is our initial public offering and no public market currently exists for our shares of common stock. We anticipate that the initial public offering price will be between $10.00 and $12.00 per share.
After the IPO there will be 361,111,491 shares of common stock outstanding at Lending Club so at 12 US$ per share this will result in a 4.33 US$ billion valuation. Read more details on Lend Academy.
This post is based on the findings, which German investor ‘Bandit55555’ posted in his own blog p2p-anlage.de. ‘Bandit55555’ is the investor at Bondora with the highest ROI (at least that I am aware of): He calculates his XIRR ROI to be 35.4%, while Bondora displays 57.5% for his portfolio. He achieves that by very diligently using the public download data supplied by Bondora as a basis for his investing and trading. In fact he even developed his own scoring system based on the data.
The secondary market of p2p lending marketplace Bondora was introduced in March 2013. Right now more than 24,400 loan parts are on sale. Using the data Bondora makes publicly available for download the following charts were created.
Number of loans sold on Bondora’s secondary market. Source p2p-anlage.de, reproduced here with permission. Continue reading →
Lending Works is an online marketplace lending platform for unsecured personal loans. We offer extremely competitive lender returns and fixed rate, flexible loans up to £25,000 over 1 to 5 years.
What are the three main advantages for investors?
Lender protection – our unique Lending Works Shield consists of a reserve fund to cover loan arrears and insurance to protect against the primary reasons for borrower defaults, including loss of employment, fraud and cybercrime. No other peer-to-peer lender offers this. In addition, our underwriting processes are extremely robust, resulting in a 0.00% arrears and default rate since launch
Great returns – our lender returns are extremely competitive and are protected by the Lending Works Shield, so the rate you see is the rate you get
Flexibility – lenders can access their funds early using our Quick Withdraw facility, or can automatically reinvest monthly repayments using Auto Lend
What are the three main advantages for borrowers?
Low cost loans – our loans are offered at market leading rates. By directly connecting our customers and cutting out the bank, we’re able to cut down the cost of a loan significantly
Simplicity – by utilising the latest technology and being an exclusively online platform, we’re able to pay out funds within one working day of completing the simple online application process
Flexibility – borrowers can make overpayments or settle their loans early at any time, without charge
What ROI can investors expect?
Lenders can expect returns of around 4.1% over 3 years, up to 6.0% over 5 years. These rates are protected by the Lending Works Shield so there shouldn’t be a need for lenders to factor in bad debts.
How did you start Lending Works? Is the company funded with venture capital?
We started building Lending Works in 2012 and launched the platform in 2014. The idea was to create a simple and safe platform to enable ordinary consumers to get a fair deal. We tried to make lending and borrowing through Lending Works as simple as possible – most of our customers do not have the time or desire to actively monitor and manage their account. That’s why we opted to steer away from an auction-based or “market†model and introduced features like Auto Lend to automate the reinvestment process.
The company is funded primarily by angel investors. We’ve raised around £4m in funding to date which has enabled us to navigate the launch period successfully. We’re now focused on driving exponential growth through innovative partnerships and new loan origination channels.
Is the technical platform self-developed?
The technical platform is completely bespoke and was initially built by an external digital services agency. Since launch we’ve brought all development activity in-house which allows us to innovate quickly and to regularly release updates. We hired our first Head of Technology, Michael Raasch, in September. Michael has over 25 years’ experience working for large investment banks and has been fundamental in preparing our platform for large scale. Continue reading →