Today Isepankur launched the possibility for lenders to sell and buy loan (parts) on a secondary marketplace. Lenders can list the loans they want to sell at the secondary marketplace and set a price which either is equal to the outstanding principal or apply a premium (up to 5%) or a discount to that. The fee Isepankur charges if a transaction closes is 1.5% (each) from seller and buyer.
I talked about the advantages a secondary market offers in p2p lending before. Most major marketplace have added the possibility to sell or buy loans. The latest to introduce this feature was Ratesetter.
In the past weeks Isepankur also introduced borrower groups (A, B and C), which group loan applications by discretionary income. Combined with the credit history classification already used (600-1000) loan applications are now classified by a combination of both (e.g. A800).
As reported earlier German p2p lending service Auxmoney completed a series A round in the end of 2012. Today the company disclosed that Union Square Ventures and Index Ventures participated in that round and invested 12 million US$. Together they hold 21,8% of the Auxmoney ownership.
Both VC have made previous investments in p2p lending companies. Union Square Ventures invested in Lending Club and Funding Circle. Index Ventures invested in Funding Circle.
CEO Raffael Johnen told P2P-Banking.com: “We are happy to have won Union Square Ventures and Index Ventures as investors. Both have comprehensive experience with online marketplaces nad their expertise will help us to accomplish our plans to grow”. Johnen plans to use the raised amount to continue development of the technology. Furthermore he want to increase the staff (currently about 30). Main goal of Aumxoney is the growth of the loan volume.
Linked Finance brings p2c lending to Ireland, enabling Irish residents (and companies) to lend to Irish companies. Borrowing companies are grouped into one of four categories (consumer, Manufacturing, industrial and agricultural, young businesses or knowledge, information technology (IT) and expertise). Linked Finance reviews each potential borrower and only allows businesses to borrow if they have successfully completed a full credit vetting process. The process is based on validating key up-to-date financial information and ensuring the creditworthiness of each borrower posted on the site. Linked Finance had start-up investment from Enterprise Ireland, and partners and investors in the venture include entrepreneurs Bobby Kerr, Senator Feargal Quinn, and Kingsley Aikins, as well as Irish American businessmen Peter Hooper and Carl Shanahan.
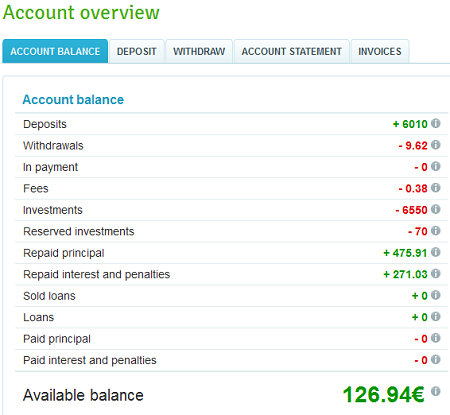
When p2p lending service Isepankur opened up to investors from all EU countries five month ago, I started lending there. In this post I continue the series of posts reviewing the development of my loan portfolio. I have deposited 6,000 Euro (approx. 7,800 US$) since starting. The account currently has 126 Euro in cash, 70 Euro waiting in bids on loans to close and 6,550 Euro is invested in loans. So far I was repaid 476 Euro principal and received 271 Euro interest.
Chart 1: Screenshot of account balance
Distribution of loans on credit grade ranges
My investment is spread out over about 350 loan parts (a bit less loans as sometimes I have 2 or 3 bids in one loan). 5,435 Euro (83%) is invested in top credit grade (“1000”) loans. 780 Euro (12%) in “900” grade loans. And the remainder are experimental bids in “600”-“800” grade loans. Continue reading →
Documents available to P2P-Banking.com show that German p2p lending service Auxmoney raised a series A round in the end of 2012 from 2 companies. The new investors now hold 21.8% of the shares, the 3 founders Philip Kamp, Raffael Johnen and Philipp Kriependorf hold 40.4% of the shares and the remainder is held by various seed investors (mainly from Austria and UK). The volume of the Series A round was not disclosed. In fact the round itself was not announced in public.
Yesterday Auxmoney did change its business model. In the past Auxmoney approach was subject to continued criticism (see also), because Auxmoneys largest fee income came from listing fees that every applicant for a loan had to pay. And with 80-90% of applications not funded, many critics felt that this model was unfair to the borrowers.
New fee model
Since yesterday Auxmoney charges borrowers a transaction fee for funded loan applications, but no more listing fees. This is in line with fee structures used by most major p2p lending services. Lenders pay a 1% transaction fee on successful bids.
No more auctions
In the past Auxmoney used a mix of loan listings that closed when they reached 100% funding and loans with reverse dutch auctions. In future all loan listings run for a maximum of 20 days and close immediately when they reach 100% funding. Raffael Johnen, co-founder of Auxmoney told P2P-Banking.com: ‘Lenders told us, that when they had bidded, they wanted to be sure to have invested in the loan part and disliked when they were outbid in the course of the auction‘.
New interface
Auxmoney also redid parts of the user interface and the dashboard for lenders. Johnen promised faster and more transparent information from the collection process. Continue reading →
Folk2Folk launches a p2p lending services for interest-only loans that are secured by first mortgages. A borrower may not use the home he lives in as security, the services aims at residential buy to let, holiday homes, commercial or industrial premises, farms and agricultural land. The loan amount can be 60% or less than the value of the security.
To start lending a minimum investment of 25,000 GBP is required. Quoted interest rates for last week range from 6 to 9%. Borrowers pay a 2% fee. Fixed term loans as well as variable length loans are possible. The concept of a p2p mortgage may sound complex, but Folk2Folk says they aim to complete the lending in 8 to 10 calender days from the time the borrower applied.
There is a very detailed set of rules describing all eventualities.