Prosper Settles Class Action Lawsuit – Pays 10M US$

In a Form 8-K SEC Filing of today, Prosper announced that it settled the class action lawsuit that has been going on since 2008 (see first coverage by P2P-Banking.com). The plaintiffs claimed that Prosper sold unregistered securities. The claimants originally filed for 47M US$. Under the settlement Prosper will pay 2 million US$ now and 8 million US$ spread out over the next 3 years.

The class members in the Lawsuit alleged that PMI offered and sold unqualified and unregistered securities in violation of the California and federal securities laws. The class members in the Lawsuit sought rescission damages against PMI and the other named defendants, as well as treble damages against PMI and the award of attorneys’ fees, litigation costs, and pre-judgment and post-judgment interest (collectively, the “Claims”). In exchange for a full release of the Claims as to all class members against all defendants, and subject to Court approval, PMI agreed to pay settlement consideration in the total amount of $10 million according to the following schedule: (i) $2 million within 10 days of entry of an order by the Court granting preliminary approval of the settlement (“Preliminary Approval”); (ii) $2 million on the one-year anniversary of Preliminary Approval; (iii) $3 million on the two-year anniversary of Preliminary Approval; and (iv) $3 million on the three-year anniversary of Preliminary Approval.

Lending Club’s Cost Advantage Over Banks

If you are not totally new to p2p lending then you probably already heard the list of competitive advantages the p2p lending services have over banks: They don’t need branches, they don’t have old legacy infrastructure/software they need to maintain, they need less staff, their processes are faster, …

But how can this advantage be quantified?

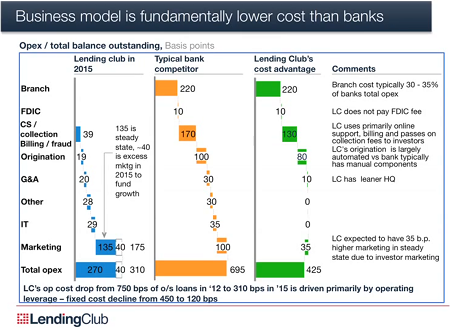
On the Lendit 2013 conference Lending Club CEO Renauld Laplanche told the audience about a study conducted by McKinsey that calculated the cost advantage Lending Club has compared to a typical bank. He showed this chart:


(Source Lending Club /Lendit 2013; view larger image)

For 2015 the chart projects a cost advantage for Lending Club of over 400 basis points over banks. This is huge. Not surpisingly Lending Club has the biggest advantages by maintaining no branches and in collection and origination. or marketing Lending Club will have higher costs than banks.

Banks will eventually embrace p2p lending

Laplanche foresees that more and more banks will actually make use of p2p lending services as platforms to invest or to fund their borrowers to profit from the faster processes and the lower costs. At the conference Laplanche announced the first cooperations with banks and says he expects more to come.

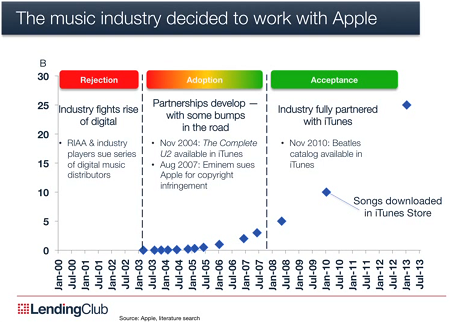
His reasoning is that p2p lending like many other innovations will pass through 3 stages: rejection, adoption and then acceptance by the incumbents. Following this argument, p2p lending could right now be early in the stage of adoption by the industry.

He showed this chart to illustrate how the music industry reacted to disruption by Apple:


(Source Lending Club /Lendit 2013; view larger image)

Zopa Announce Business Loans

Zopa has announced that they will start to offer business loans soon. Zopa will start with loans to sole traders.

Soon we will introduce business loans to Zopa, offering good value loans to sole traders.

We’ve chosen to start our business loans with sole traders for two reasons:
1. We saw that there were few opportunities for smart sole traders, with a good credit and trading history, to access good-value loans.
2. Sole traders are often looking for loans of a similar size and time period as our personal loan borrowers so offering these loans doesn’t require big changes for our savers to the way they choose to lend

Milaap Raises 1.1M US$

P2P microfinance service Milaap (see earlier coverage on P2P-Banking.com) raised 1.1 million US$ from Jungle Ventures (Singapore), Toivo Annus,Lionrock Capital, Jayesh Parekh and Unitus Seed Fund. The current round of funds will be utilized to expand engineering and marketing investments for enhancing the online product experience, and to invest in scaling up marketing and outreach efforts.

Milaap says that so far 100% of the microfinance loans originated have been paid back.

Ratesetter Raises 5M Funding – Valued at over 30M

Ratesetter has raised 5 million GBP funding in June from existing shareholders, who include Peel Hunt founder Charles Peel, fund manager John Chatfeild-Roberts and Lazard chairman Ken Costa, plus a new Hong Kong-based investor. The founder Peter Behrens and Rhydian Lewis still own an almost 40% stake in the company which in this round had a valuation of more than 30 million GBP. Ratesetter, which aims to fund over 100 million GBP in p2p loans this year, reached break-even in January and will use the new capital to foster further growth.

(Source: Lucy Tobin, London Evening Standard, July 1st 2013)

P2P Lending: How are interest rates set?

Everybody talks about the win-win situation p2p lending offers for lenders and borrowers. By cutting out the large spread a bank takes when making a loan, the lender can get a higher interest rate, than he might in a savings account and the borrower may get a lower interest rate, than using his credit card. But who does actually decide what the interest rate for a p2p loan will be?

Several market mechanisms have developed. P2P lending services use combinations of these to built their platforms. I’ll describe some of the elements:

Individual Loan Listings vs Markets: With Listings (e.g. Prosper, Lending Club, Auxmoney, Isepankur) lenders can look at individual loan listings and see multiple parameters (e.g. credit grade, income, DTI, occupation, location,…). The lender can select (“filter”) loans based on his strategy. This is not necessarily a manual process as he can opt to use automatic bidding tools that make the selection for him based on criteria he set in advance. Other p2p lending services use Markets (e.g. Zopa, Ratesetter) which combine loans based on broader criteria (e.g. loan term, or credit grade). Here a lender can only decide which market to invest into, but does not pick individual loans.

Close at Funding vs Auctions: Some p2p lending services close loan listings once they are 100% funded. The loan is then originated. Others uses an auction process where the listing is open for bidding for a set time. If the loan amount is 100% funded then the bidding continues for the remaining auction period. New bids at lower interest rates push out old bids at higher interest rates, thereby lowering the final interest rate for the borrower. Some p2p lending services allow loan listings of both types or let the borrower prematurely end an auction (e.g. Rebuildingsociety, Isepankur, Assetz Capital).

Uniform vs Mixed Lender Rates: After an auction the interest rate for the borrower can be set at the rate of the highest successful bid. In this case all lenders on the same loan get the same uniform interest rate (e.g. Isepankur). Another option is to calculate the interest rate as an aggregate of all successful auction bids. In this case each lender gets the rate he did bid – there will be a wide mix of lender interest rates on the same loan (e.g. Rebuildingsociety).

Who does decide what the interest rate will be on a p2p loan

I. Borrower sets interest rate

The borrower decides, what (maximum) interest rate he is willing to pay (e.g. Smava, Auxmoney, Isepankur). The lenders can then decide, if they want to fund this specific loan at that rate or not. If there is an auction and lender demand is strong, then the borrower may get the loan for a lower interest rate then specified. Obviously lenders will fund loans with most attractive rates first and other loans will go unfunded. These borrowers can react by relisting at a higher interest rate. Continue reading →