My Lendit Europe 2016 Recap

I attended Lendit Europe in London the last days, an industry event of the p2p lending (or marketplace lending) industry. This was my third Lendit and it was not only bigger (904 attendees from about 180 companies) but again better than the previous year.

Samir Desai, CEO of Funding Circle in his opening keynote sees it as the golden age of the industry. And that certainly is the sentiment that much of the British part of the market would agree with. However there is headwind to be countered. The P2PFA, the association of the UK marketplaces that co-hosts the event, comissioned a report on the economics of peer to peer lending. Christine Farnish, the Chair of the P2PFA said that they did this to rebuke assertions by facts and counter comments by the tradional industry about risks.

The new Oxera report is available for free download here. Reinder van Dijk presented the findings of the report which focuses on the eight members of the P2PFA. He showed based on data, that in general the platforms did a good job on assessing risk, as the actual defaults for the years 2013 and 2014 were mostly in line or lower to the predictions the marketplaces made beforehand.

Lord Turner, former head of the UK Financial Services Authority created a media stir earlier this year with a very critical remark on p2p lending. In his keynote speech Turner did a turnaround saying he had not fully understood the p2p lending model in detail at that time and that he thought the interview was over when he made the comment. His final message to the marketplaces is keep it simple and transparent.
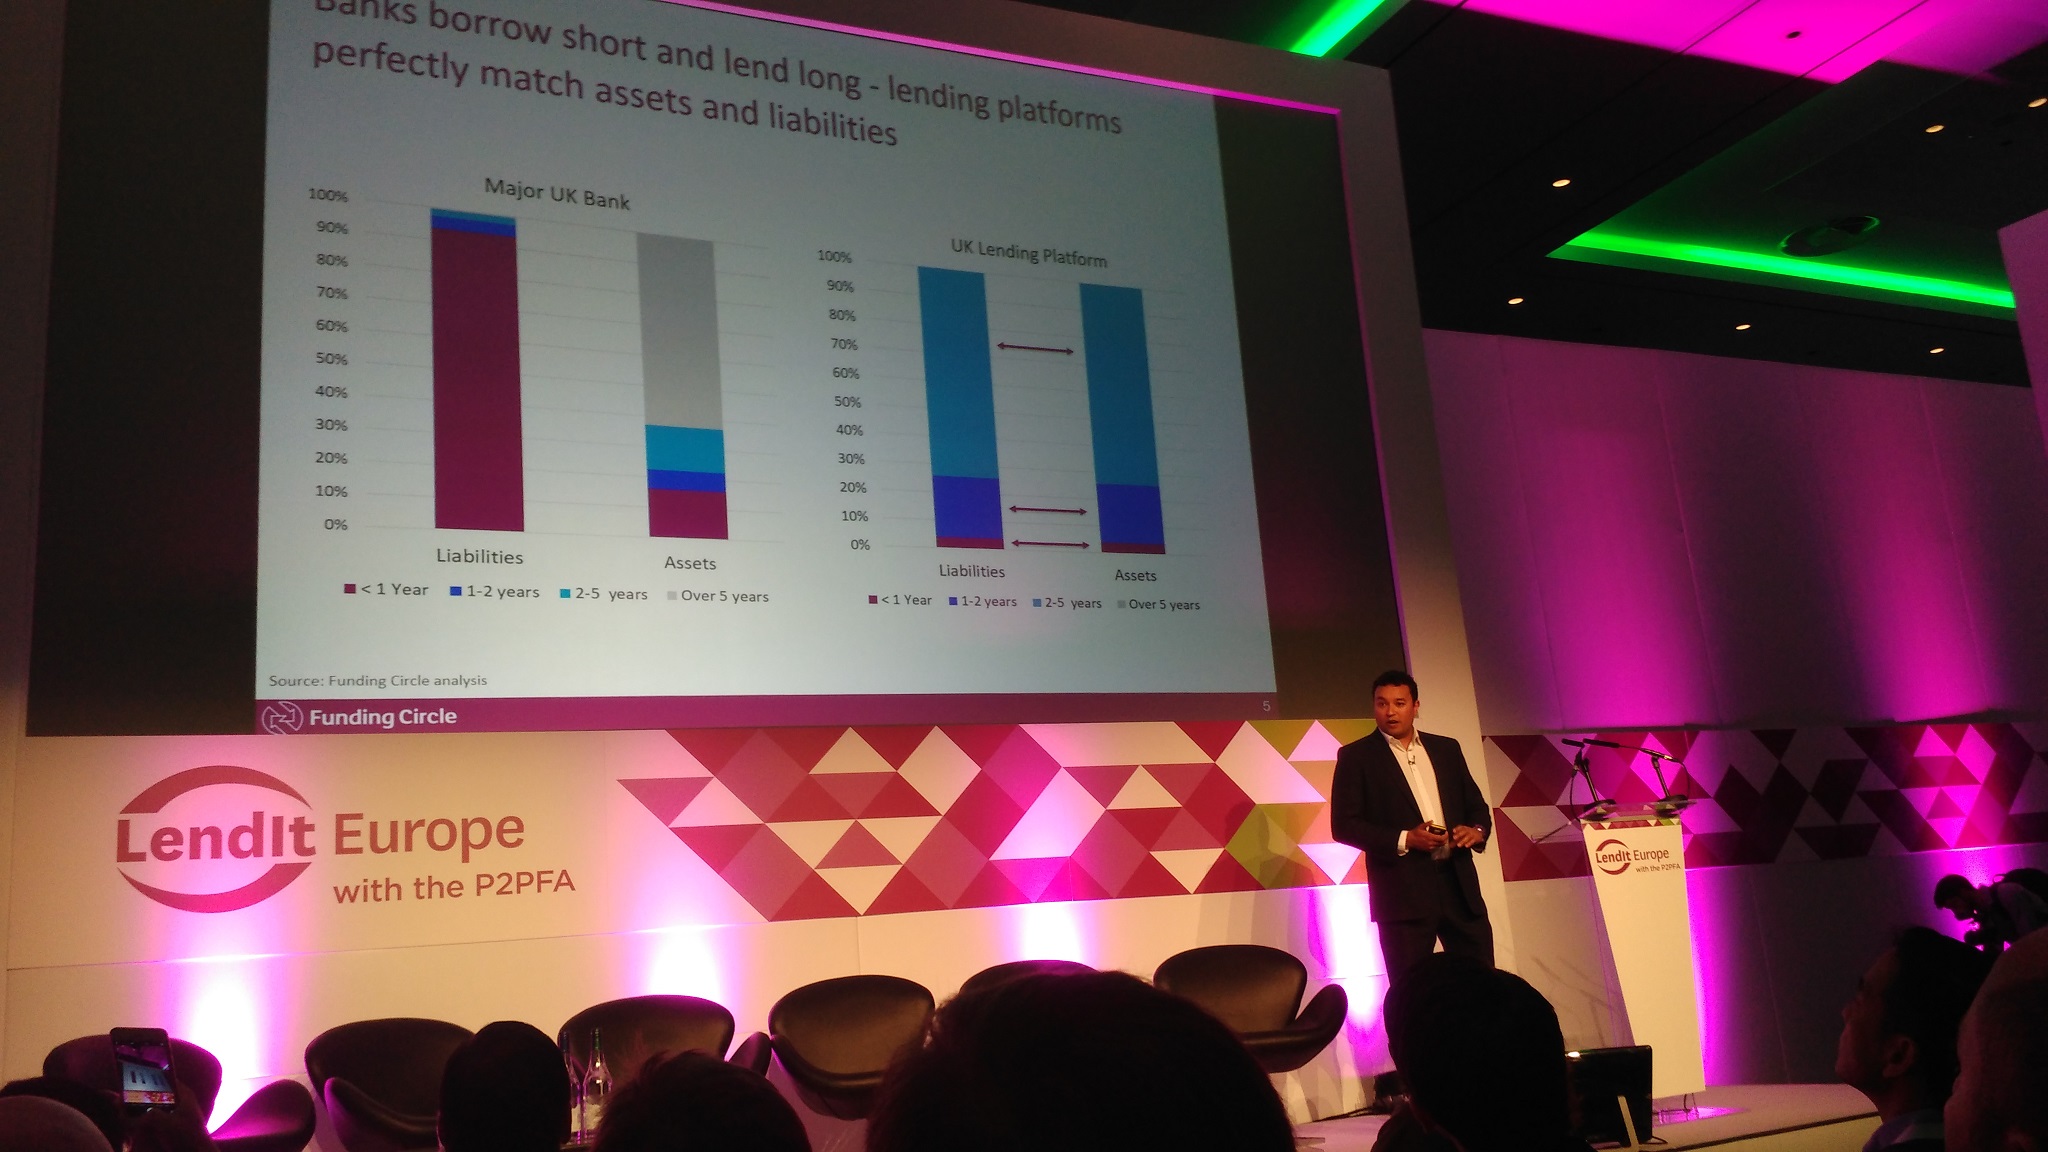
Lendit 2016
Impression from Lendit 2016 (own photo)

One major topic for the UK players is when FCA approval and the launch of the IF ISAs will occur. There is a feeling – but no certainty – that it’s getting closer. Farnish says she expects IF ISAs to be available by spring 2017. I also asked several people whether they expect it to be a big bang event, meaning that all the big players get approval at the same time to launch their ISA offer. Again there is no certainty but most respondents said they feel it would be only fair to grant the approval simultaneously because otherwise the first starter would have quite an advantage.

By the way most of the sessions, panels and demos are available here as videos and can be watched free. I recommend Cormac Leech’s keynote as a data rich, not easy to digest, but highly informative appetizer. Then for a second course with some added spice injected by Kadhim Shubber, FT, watch James Meekings of Funding Circle, Giles Andrews of Zopa, Peter Behrens of Ratesetter, Christian Faes of Lendinvest and Anil Stocker of Marketinvoice here. And for a maximum of contradicting opinions during one panel you might finish here, where Cormac Leech suggests that p2p lending marketplaces should monetize by ‘bombarding’ users with cross selling offers, not only for fintech related offers but for example also selling holidays. He think the bombarded users would be receptive if only the marketplace at the same time gives them a better rate. (I might be compressing his argumentation, please watch it in full). This to me is a stretch. I think that p2p lending marketplaces should deliver what the investors expect from them: great returns. Surely there is some opportunity for cross-selling with related financial products. On the other hand I do believe that the challenger bank (Monzo) present in this panel has some merit with it’s plan to analyse data to make fitting offers based on the budget and the spending pattern of the customer. Will that appeal to everybody? Certainly not. But the customers that will sign up with them are looking for a change from their previous banking experience so they might be open to that.

Another argument was on ‘pure’ marketplace lending model versus hybrid versus balance sheet based lending. While there are different opinions and preferences voiced, several speakers thought that there will be players of each type that are succeeding.

I actually missed many of the afternoon sessions of the first day, because one main benefit of Lendit for me is the networking opportunity. I talked to many marketplaces I knew, to keep up with their developments and plans, and made contact with new marketplaces. My view is a bit biased on topics of interest of retail investors from the continent so I am overweighting platforms news that are revelant to these in the following paragraph.

I checked with Saving Stream and they confirmed that they will lower interest rates with the intention to win more borrowers. The one size fits it all rate will be gone which takes away some of the straightforwardness/ease of use. I wasn’t told how much lower rates will go and on my question whether rates will vary depending on the loan risk, the answer was that this is yet undecided. Ed of Moneything said progress to growing loan volumes even further is good. Investly will disclose a new UI for investors soon. Aurora Exchange from Finland says it will not only launch there but will be able to serve all of Europe (not only from the investor side but also on the borrower side).

I had so many conversations, that I missed most of the Pitchit, which I had really looked forward to see. But I was in time to see the pitch by Lendingwell which was very good and as it turned out the next day that was the pitch that won.

I had the pleasure to moderate a panel on up and coming European platforms, this year featuring Creditshelf, Giromatch, Finbee and Viventor. I am looking forward to next year and am curious which great event location Peter Renton and his team will scout next time.
lendit-london-o2-sm

International P2P Lending Services – Loan Volumes September 2016

The following chart lists the loan originations of p2p lending marketplaces in September. This month I added Crowdestate. Funding Circle, Ratesetter and Zopa had a record month. The total volume for the reported marketplaces adds up to 424 million Euro. I track the development of p2p lending volumes for many countries. Since I already have most of the data on file I can publish statistics on the monthly loan originations for selected p2p lending services. Milestones in total volume originated since inception:

Investors living in national markets with no or limited selection of local p2p lending services can check this list of marketplaces open to international investors. Investors can also explore how to make use of current p2p lending cashback offers available.

P2P Lending Statistic Sep. 2016
Table: P2P Lending Volumes in September 2016. Source: own research
Note that volumes have been converted from local currency to Euro for the sake of comparison. Some figures are estimates/approximations. The Wellesley volume is 0 for this month – this may be a reporting error.
*Prosper and Lending Club no longer publish origination data for the most recent month.

Notice to p2p lending services not listed: Continue reading →

Smava Raises 34M US$ Series C

smava-logo-2016German credit broker Smava today announced that it has closed a 34 million US$ investment which was led by growth investor Runa Capital, with additional participation from Verdane Capital and mojo.capital. Runa Capital is a venture capital firm with other investments in Zopa, Lendingrobot and Lendio. Verdane Capital is a Scandinavian private equity firm. Existing investors including Earlybird Venture Capital also participated in the investment. This series C round follows the previous round in 2015 which was 16 million US$. In total Smava, which launched in 2007, has raised about 64 million US$ so far.

Smava wants to use the funding to expand the customer base, hire additional talent and continue enhancing our scoring technology according to CEO Alexander Artopé.

Smava connects private borrowers with a broad selection of banks and private investors on its marketplace. Smava offers personal loans ranging from 1,000 to 120,000 Euros. Continue reading →

Prosper Closes Secondary Market

prosper-logo-2016P2P lending marketplace Prosper today informed investors via email, that it will close down the secondary market, effective October 27th. Prosper does not operate the secondary market itself, but uses FolioFn, operated and maintained by FOLIOfn Investments, Inc., a registered broker-dealer.

The announcement email reads:

A Message from Prosper and Folio Investing

Dear …,

We are writing to let you know that as of October 27, 2016, Prosper will no longer offer the Folio Investing Note Trader platform, the secondary market for Prosper Notes. Prosper has found over time that very few investors are using the secondary market and, as such, has made the decision to no longer offer this service. We apologize for any inconvenience that this causes. Prosper remains committed to its retail investor clients and to providing them a great experience.

Here’s what this means for you: The secondary market trading service will be available as normal until end of day (5:30 pm PST) October 19, 2016. After that time, any new orders to list Notes for sale will not have sufficient time to be completed and processed before the site becomes unavailable to users at the end of day (5:30 pm PST) on October 27, 2016.

Once the secondary market trading service is terminated, you will not be able to sell Notes that you own, and you will need to hold them to maturity.

If you have questions about your Notes or the wind-down of the Folio Investing Note Trader platform, please contact Prosper customer service at 877-611-8797.

Thank you.

Prosper and Folio Investing

Prosper has not disclosed usage numbers of the secondary market in the past, but volume traded is perceived to be low and this is also stated in the email. One speculation is that Prosper decided to close the secondary market to cut costs.

My feeling is that this will deliver a blow to the attractiveness of the Prosper marketplace for retail investors. Even if many investors have choosen not to use the marketplace (which several report does not have a very good user interface) the fact that there is a marketplace delivered some assurance that they could exit at least a larger portion of their portfolios should the need for liquidity arise. Also a one month notice seems to me rather short, given that loans can run up to 60 months and with the changed perception the prices could sink (lower markups, higher discounts) in the remaining month of trading as the number of investors wishing to use this last chance to sell will rise in my view, while the number of investors buying will at best stay stable. Continue reading →

My Bondmason Test – Review at Start

bondmason-logoI decided to try out another UK p2p lending service. Bondmason is not a marketplace facilitating loans itself, but rather acts as intermediary steering and automating investments for the users. Bondmason wants to offer an easy way to automatically invest and diversify. To allow this, I need to hand over full control to Bondmason. In return Bondmason projects a target return of 7% after fees and bad debt. Note that the target return is not guaranteed.

Getting started was easy. I deposited the minimum amount of 1,000 GBP. Since I am in the Eurozone I used Transferwise to do this in order to avoid high bank fees. For higher amounts Currencyfair can be cheaper. After two days Bondmason notified me via email that my money arrived. After login I saw that the service already invested 180 GBP in the first 9 selected loans.

Bondmason invests in sme loans, property loans and invoice discounting. Currently Bondmason is using 19 marketplaces, but does not disclose which ones are used arguing IP considerations. Some of them do not seem “typcial” p2p lending marketplaces, as one mentioned example is Fiduciam. As in investor I am only shown nominal interest rate, type of loan and term.

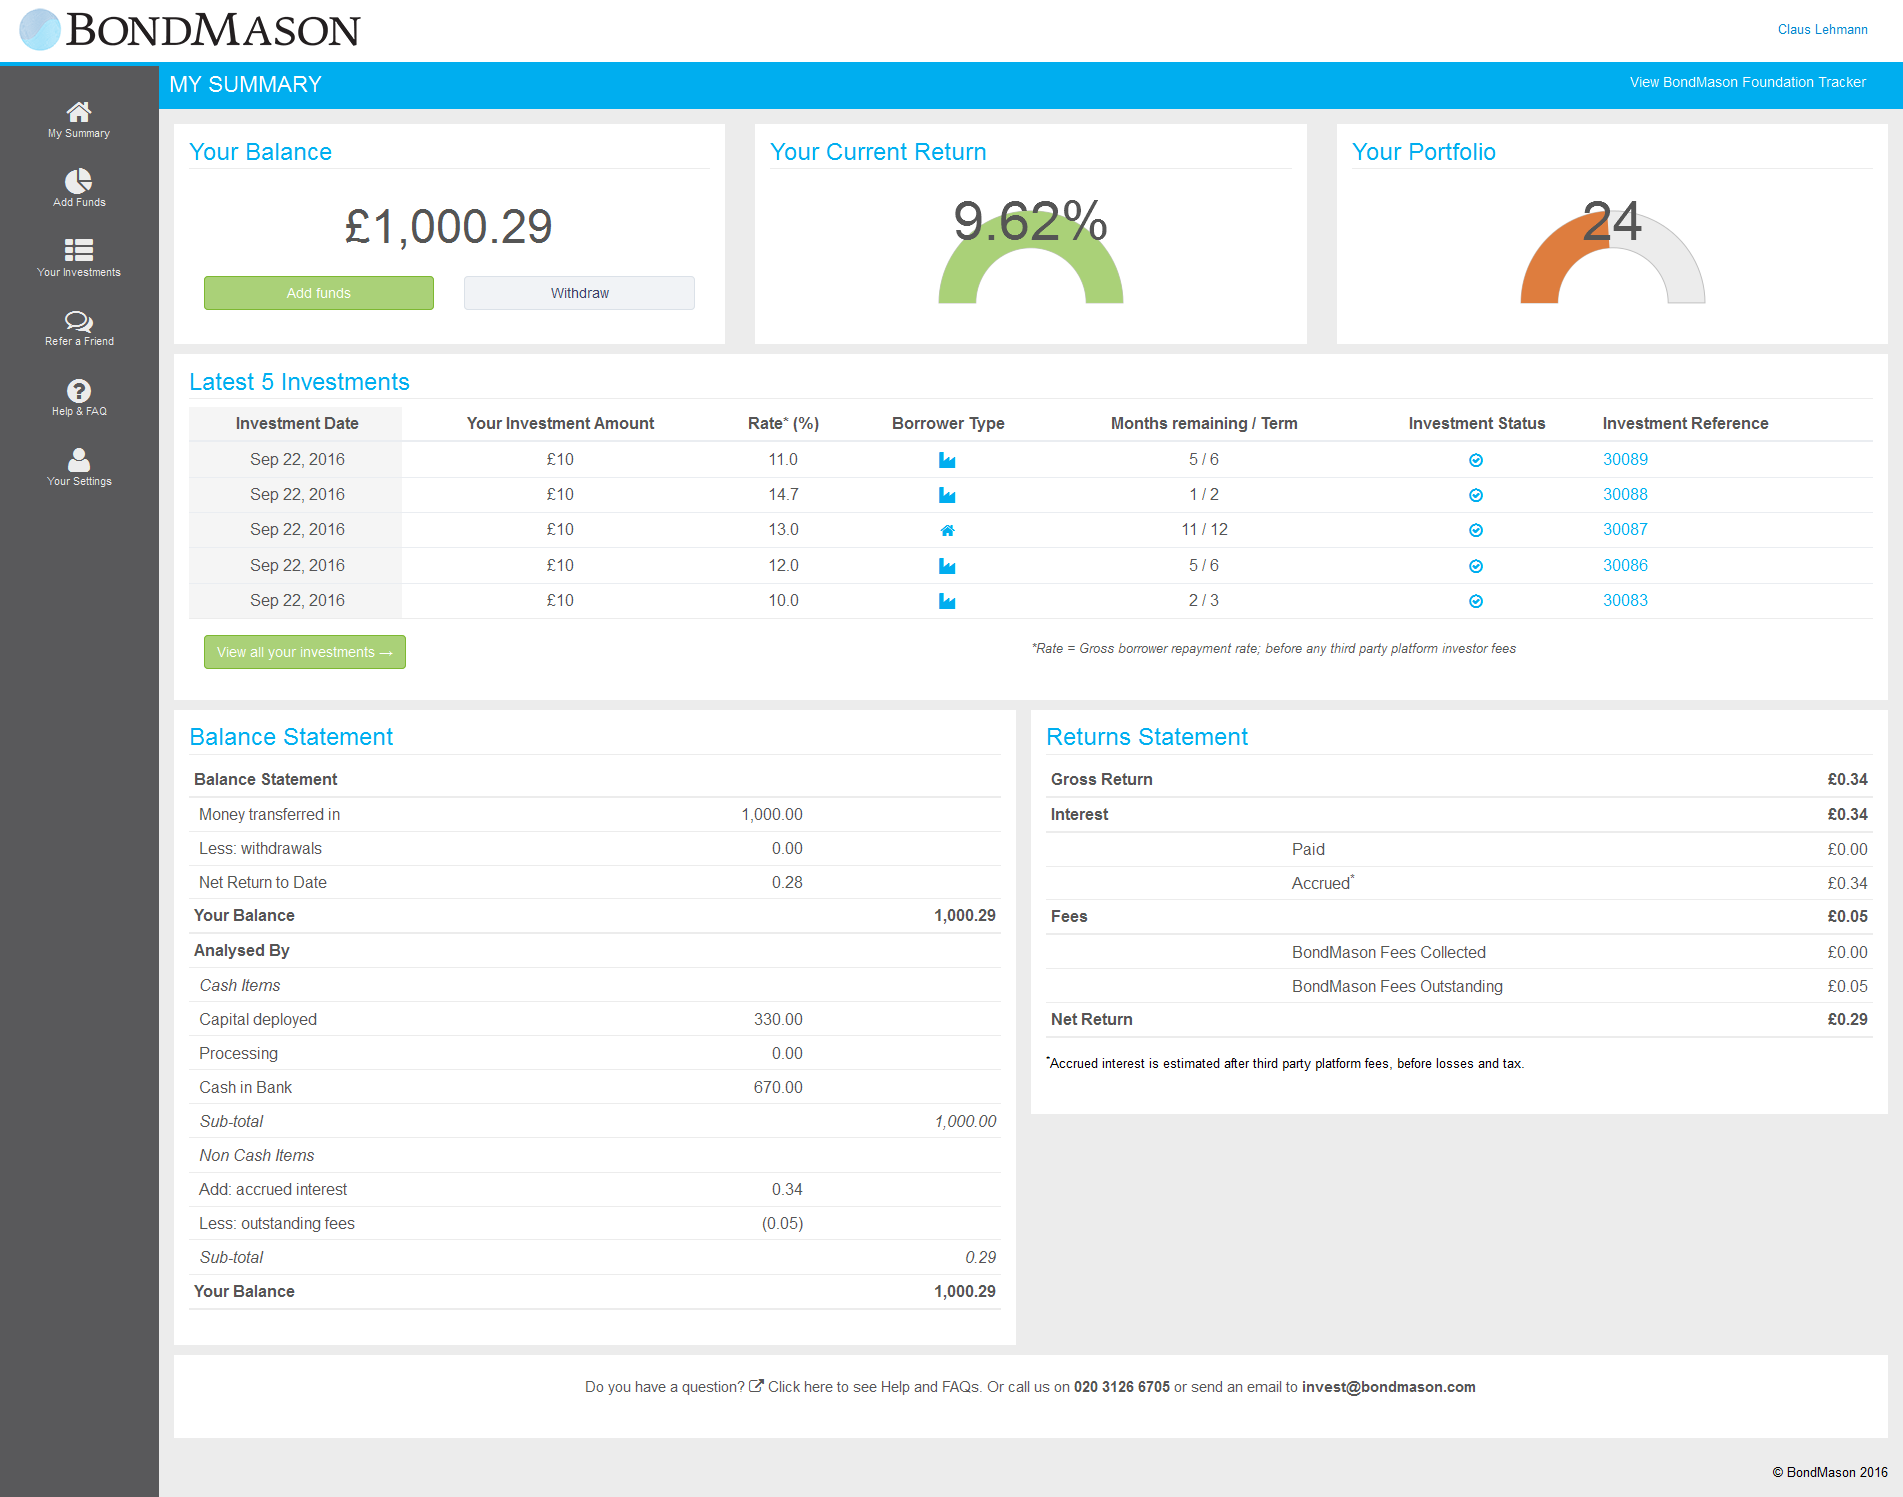
My Bondmason dashboardMy Bondmason dashboard on day 6 after start (click to enlarge)

The information provided is rather minimalistic, there are really only two views. The dashboard view (see above) and the investment view (see below). Regarding parameters there is only the choice whether to reinvest and the diversification setting, which lets me select a maximum of 2% or 1% investment concentration. There is no account statement.

So far Bondmason invested 330 GBP (or 33%) of my cash. The selected loans have nominal interest rates ranging form 6.0% to 14.7% and terms between 1 and 13 months. As an investor I have to fully trust the loan quality and loan selection provided by Bondmason to deliver the promised target return. Since (so far) all my loans are bullet loans, it will take me even longer to find out how high bad debt levels will be in reality. But that’s what this test is for and I’ll continue to report on my Bondmason experiences.

This page gives some more information on the approach of the algorithm in loan allocation. Bondmason targets one third loans with less than 60 days, one third with up to 12 months term and one third over 12 months term for my portfolio. Continue reading →

Ratesetter Reports Rising Revenue & Pre-Tax Loss

Peer-to-peer lending platform RateSetter has published its 2015-16 accounts, showing that it increased revenues from 12.6M to 18.5M GBP over the year. The company made a pre-tax loss of 4.9M GBP, compared to a pre-tax profit of 476K GBP for the preceding year. The company’s results are in line with expectations set out at the start of the year and reflect the decision to charge more fees over the lifetime of loans rather than upfront and a planned increase in investment back into the business.

Loans under management increased by 70 per cent, from 341M GBP on 31 March 2015, to 581M a year later, while the number of active investors grew from 18,608 to 31,036 over the same period. Today these figures stand at 640M GBP and 36,310 respectively – with a 70 per cent increase in new active investors in the period since the EU referendum compared to the same three months last year.

RateSetter made a profit for the years ending 31 March 2014 and 2015.

One of the main investment considerations for the money raised in 2015 from a consortium of investors including Woodford and Artemis was to alter the timing of receiving income: in 2015 RateSetter started to charge a greater proportion of its fees over the lifetime of loans rather than purely up front when loans are written. This creates a more sustainable recurring income stream as more money comes in over the term of loans, reducing pressure to lend in order to generate revenue when credit conditions are poor. Importantly, it also aligns RateSetter’s interests with those of its investors as it provides a financial incentive to only approve loans which perform. If all fees had been taken upfront when loans were written, rather than charged over the lifetime of loans, RateSetter would have recorded a pre-tax profit in 2015-16. Continue reading →