In the Case of Death

‘What happens when I die’ is a concern occasionaly voiced by investors. Investments in p2p lending will be inherited like any other assets. The concern for the investor is how readily their beloved ones will be able to access the funds. I scanned the FAQs of several p2p lending marketplaces but this is not one of the topics addressed. I then reached out to the marketplaces asking for information.

Ratesetter, Assetz Capital and Estateguru pointed out that the procedures are very similar to those applied by other financial institutions.

Assetz Capital, after being notified about a death of an investor by the next of kin or a solicitor acting on behalf of the deceased estate will mark the account as deceased and suspend all marketing emails. The next step is requesting proof of death, most commonly provided in form of a death certificate and grant of probate. In the event that the decision taken is to liquidate the account then all account holdings are put up for sale. Any funds which can be released immediately are sent to the appropriate recipient and a monthly sweep of the account is carried out indefinitely until such time as all funds have been liquidated and released to the appropriate recipient.

Luke O’Mahoney of Ratesetter explained: ‘If an investor dies, we work with the next of kin to establish how they would like the account to be dealt with. Generally they would either use our Sellout function (effectively liquidating their investment) or they would allow the account to run down over time – of course we assist the next of kin or executor with this process’.

Funding Circle CE answered: ‘If the account is transferred the inheritance would need to be proven and the account would be manually transferred. The heir can then decide what to do with the portfolio.’

Martins Sulte, CEO of Mintos indicated that there are numerous different situations as the account is inherited according to the respective laws of the country where the investor resides.

In Estonia all matters of inheritence are usually dealt with by a notary office or a solicitor, says Aleksei Kurov of Estateguru. He describes ‘[the] notary or solicitor sends requests to different registers: Property Register, Companies House including all credit/finance institutions to clarify if the person in question had any obligations or deposit/investments accounts opened and what are obligations or funds are connected to these accounts. … When all heir/heirs are clearly identified and the amount of inheritance is also clarified then Notary Office is making a registry entry to an Inheritance Register. This entry will specify the list of heirs and their share of the inheritance. EstateGuru will have an information about the death and consequent inheritance procedures when we are contacted by Notary or Solicitors office. Then we will check with Inheritance Register (if the investor is from Estonia) or with according local institution to confirm this information. We will also seek independent confirmation from his Bank, which was used to transfer funds to our account. Any monetary pay-out or change the information of the account owner is possible only after we receive an official and apostilled confirmation from notary office, solicitors and/or double check this information with available local Inheritance Registry. If information we received is in local language, we will request that it is translated into English and apostilled. If we are satisfied with the identity confirmation and the legal rights heir/heirs then we will follow instructions from them, to make necessary changes on the account, close it or do the pay-out of available funds.Already invested funds will be repaid at the project maturity.’ Continue reading →
International P2P Lending Services – Loan Volumes June 2016

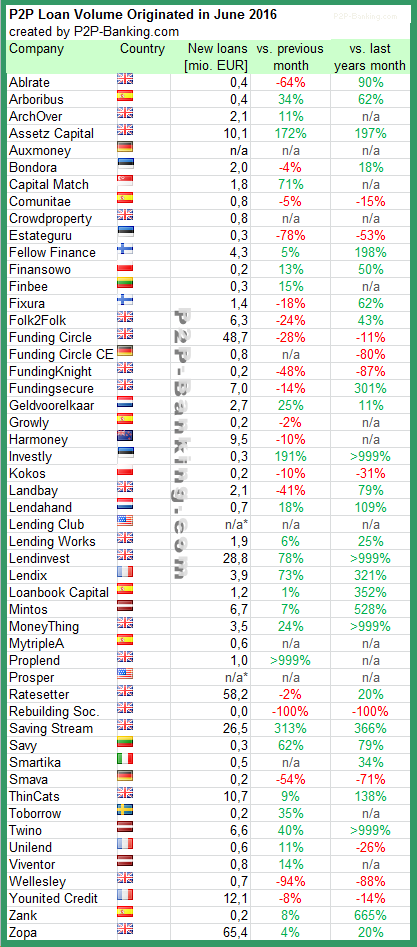
The following table lists the loan originations of p2p lending platforms in June. Zopa leads ahead of Ratesetter and Funding Circle. This month I added MytripleA. The total volume for the reported marketplaces adds up to 334 million Euro. I track the development of p2p lending volumes for many markets. Since I already have most of the data on file I can publish statistics on the monthly loan originations for selected p2p lending platforms.

Investors living in markets with no or limited choice of local p2p lending services can check this list of marketplaces open to international investors. Investors can also check how to make use of current p2p lending cashback offers available.

P2P Lending Statistic 06/2016

Table: P2P Lending Volumes in June 2016. Source: own research
Note that volumes have been converted from local currency to Euro for the sake of comparison. Some figures are estimates/approximations.
*Prosper and Lending Club no longer publish origination data for the most recent month.

Notice to p2p lending services not listed: Continue reading →

German Investors Look Beyond Borders when Using P2P Lending

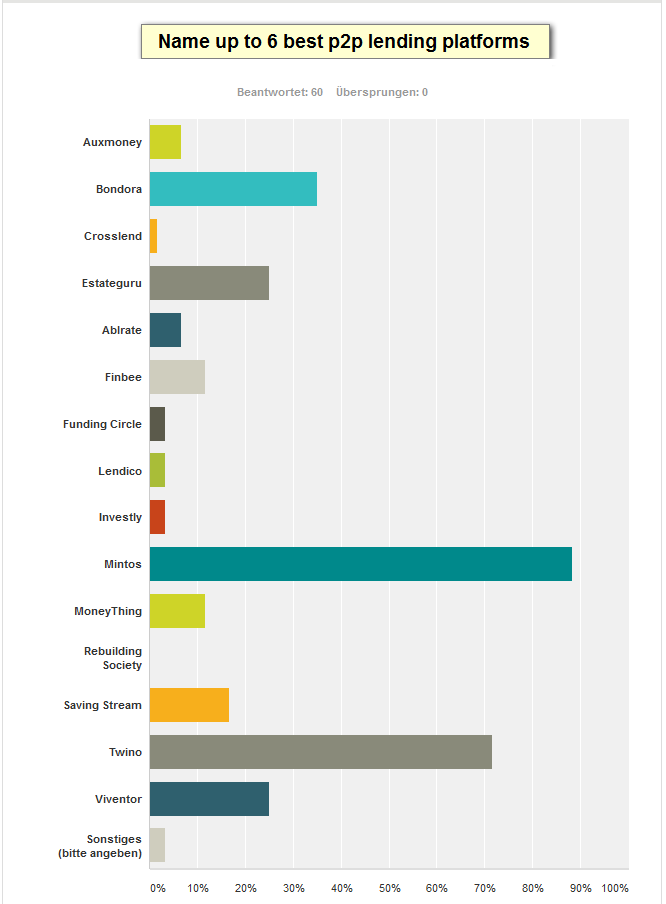
A poll conducted by P2P-Kredite.com among seasoned German speaking investors found, that many prefer p2p lending platforms outside the country they live in. After getting accustomed to the p2p lending concept and liking it, they are on a hunt for higher yields. Further supporting factors are the offered English language interface (a language most understand well), the easy transfer of funds within the Eurozone by SEPA payments and more features offered, e.g. most foreign platforms offer a secondary market, while currently none of the German marketplaces do.

German poll
Poll by P2P-Kredite.com, conducted in June 2016. 60 respondents. Each respondent could name up to 6 platforms. Note that Funding Circle refers to the German platform of Funding Circle, not Funding Circle UK.

Mintos (53 votes) and Twino (43 votes) lead by a wide margin in preference of the respondents, followed then by Bondora (21), Estateguru (15), Viventor (15), Saving Stream (10), Moneything (7) and Finbee (7).
Exclusively baltic and british platforms rank best among the respondents. The choice of british platforms for German investors is limited though as some like Zopa or Ratesetter are open only to UK residents or require a UK bank account to sign up.
Nearly all votes were cast before the Brexit decision. It remains to be seen how the UK platforms will rank in German investor preference in the future, given the more volatile GBP/EUR rates and the increased uncertainty for the UK economy.

How the Brexit Influences My Personal P2P Investment Strategy

Well that was a surprise. When I went to bed last midnight the news reported more indications for a remain vote than for a leave. Even with psephologists cautioning that the referendum is very hard to predict due to the lack of comparision data from earlier votes, it seemed to me that the outcome was likely pro EU.

While I had personally wished the Brits to stay in the Union they took a democratic decision and now the politicans have to act upon it to execute divorce.

Awakening to the new reality I now have to assess what this means for my personal p2p investment strategy – as a foreign investor. Only a small portion of my p2p investment portfolio is invested in UK platforms (a substantial amount at Saving Stream, small amounts with Ablrate, MoneyThing and Rebuilding Society). The markets are in turmoil, and I have already taken the hit by the pound dropping sharply compared to the Euro this night.

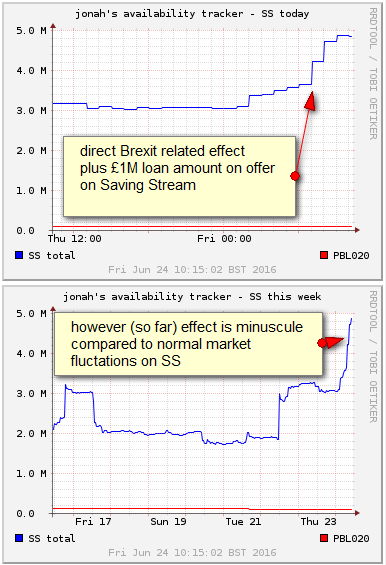
Another effect is that the uncertainty is causing more investors to put up loan parts for sale – the effect is measureable on Saving Stream and currently accounts for a plus of approx. 1M GBP loans on offer there. Still this amount is very small compared to fluctations of liquidity levels due to other factors. For most loans this now means that there is a considerable delay in selling loans, due to queue size. However this could be cleared up quickly by one or two large loans repaying and the interest payout on July 1st.

Saving Stream loan tracker
(Source: jonah; own edits)

With Saving Stream and Moneything loans will depend highly on the development of the property prices. Some expect a drop in property prices. I think it is to early to tell if that will happen, but I think it is very likely that there will be slow down in new development activity while everbody waits to see what the outcome will be. This will affect the demand for bridging loans and thereby Saving Stream and Moneything to a cetain degree.

And then totally unpredictable there is the question how this new direction will effect the European economy as a whole and whether it might trigger a recession. While I am optimistic that it will not, there is an extreme amount of uncertainty and I have to consider that this might impact my p2p investments on continental European platforms.

For now I have decided that I will not deposit new funds on UK platforms (which I was planning to do) but will not withdraw funds either at the moment and will just keep reinvesting the proceeds. I see little point in selling off loans (would be hard right now anyhow as liquidity seems to dry off temporarily), and exchange the amounts back to Euro. That would guard me from further drops of the pound exchange rate, but I think it is not sure that the pound will fall into a continuing decline (even so that seems more likely than any rise in the pound rate vs the Euro).

For the continental platforms my strategy remains unchanged by the event, even though I think that the risks on some platforms have risen somewhat too in the mid-term outlook.


Commerzbank will Launch P2P Lending Platform Main Funders Next Week

At a press conference this morning in Frankfurt, Michael Kotzbauer of Germany’s second largest bank Commerzbank and Birgit Storz of Main Incubator announced that the new platform Main Funders will launch next week. Main Funders is part of a broader digitalisation strategy of Commerzbank and the first project Commerzbank and Main Incubator built together. Main Incubator previously invested in several Fintech startups.

The aim of the new platform is to bring together SMEs seeking loans in the range of 200K to 10M Euro for up to 5 years and professional investors (institutional and large companies). Both will be already customers of Commerzbank and Commerzbank will make use of its regional sales force to bring borrowers onto the marketplace.

Kotzbauer explains strateg of Commerzbank with context Main FundersBorrowers will list their project n the platform, visible only to logged in investors, which in can browse the listings and select those that match their interests. Main Funders will assign credit grades to the loan requests and set the interest rate, taking into account that all loans will be unsecured. Since borrowers already have a credit history with Commerzbank, Storz says that the process, including the handling of the contracts, will take only a short time frame.

Main funders charges borrowers 0.45% of the loan amount multiplied with the duration and  investors 0.2%.

Unlike on other platforms investors won’t have to ‘park’ cash to be able to invest but rather will be able to pay for funded loans after all contracts have been signed, an advantage to avoid cash drag.

Once the loan is fully funded, the loan will be serviced by a third company (not Commerzbank or Main Funders).

Main Funders says it is uniquely positioned compared to other p2p lending marketplaces in that it is able to facilitate very large loans and benefits from the relationship and trust Commerbank already has to target customers.

With Main Funders Commerzbank aimes to:

  • increase customer satisfaction
  • strengthen its competitive position
  • react to rgulatory requirements
  • create a basis that will allow it to build further innovative loan products upon

Storz declined to give a figure on the expected loan volume in the first year, saying it is important to be able to react and adapt quickly in such an innovative product offering.

Some questions in the press conference targeted whether Commerzbank is cannibalizing the own products and if there is no conflict of interest in the decision of whether to finance a loan itself or put it on the platform.

Kotzbauer said that Commerzbank is reacting to the wish of some of their customer to diversify financing options. The decision of whether to finance the loan request themselves or put it on the platform is made after consulting with the borrower on his financing needs and wishes and not discriminating by credit grades or other parameters.

Main FundersCommerzbank is one of the first large banks in the world to have developed its own platform (together with its incubator). Other banks have taken the route to acquire lending startups (e.g. Barclay Africa Rainfin, Westpac with SocietyOne, or Banca Sella at Smava and Prestiamoci). Several banks are investing into consumer and SME loans on p2p lending marketplaces, especially in the US and the UK.

The initiative of Commerzbank is likely going to give a boost to awareness and credibility of p2p lending in Germany, even though it remains close to the conventional process with the restriction to existing customers and institutional investors. Continue reading →

International P2P Lending Services – Loan Volumes May 2016

The following table lists the loan originations of p2p lending marketplaces in May. Funding Circle leads ahead of Zopa and Ratesetter. I track the development of p2p lending volumes for many markets. Since I already have most of the data on file I can publish statistics on the monthly loan originations for selected p2p lending platforms.

Investors living in markets with no or limited choice of local p2p lending services can check this list of marketplaces open to international investors. Investors can also check how to make use of current p2p lending cashback offers available.

P2P lending Volume May 2016

Table: P2P Lending Volumes in May 2016. Source: own research
Note that volumes have been converted from local currency to Euro for the sake of comparison. Some figures are estimates/approximations.
*Prosper and Lending Club no longer publish origination data for the most recent month.

Notice to p2p lending services not listed: Continue reading →