Fairplace – P2P Lending in Brazil

Fairplace.com.br recently launched the first p2p lending service in Brazil. With approx. 190 million inhabitants Brazil could prove an interesting market for peer to peer lending. While financial institutions are the most common source for loans, consumers face lots of paperwork and high interest.

Founder Eldes Matiuzzo knows that, for he worked 14 years for Unibanco. He says user response since the launch is promising with about 25 registrations per day.

Each loan application undergoes risk assessment (Fairplace uses Seresa Experian Data) and only about 20 percent of applications are approved.

Loan requests are listed for a 14 day auction. Borrowers pay fees only if the loan is successfully funded. Fees listed are 5% for one year loans and 8 percent for two year loans. There are additional fees for credit assessment and each repayment installment. Lenders are charged 2% of each repayment (repaid principal + interest).

Currently the average interest rate at Fairplace is 2.99 percent per month, which is much lower than the average for the Brazilian market.

Vittana Credit

Education microfinance service Vittana.org (see earlier coverage about Vittana) now enables lenders to relend directly. Lenders no longer need to go through Paypal for  every payment and repayment.

CEO Kushal Chakrabarti says: “Today, I have the honor of announcing that, as of last week, Vittana lenders had given over 200,000 US$ in loans to hundreds of young people who want to become engineers, policemen, biologists and much more.”

P2P Lending Topic in German Parliament

In German the “green” party has initiated a parliament inquiry asking the government to ask 25 questions regarding it’s position towards p2p lending. While the party in the preamble describes p2p lending as a chance for consumers potentially offering them more choices, the wording of most of the questions exhibits that the green party is mostly concerned about the risks and implies that p2p lending is not enough regulated.

(Source: P2P-Kredite.com)

P2P Lending With Cars as Collateral

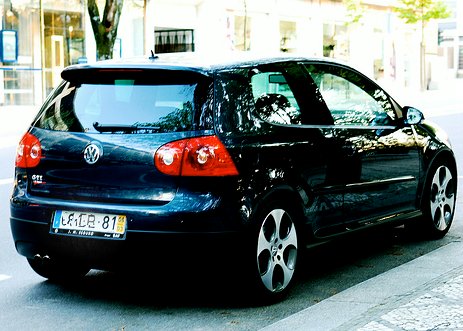
German p2p lending service Auxmoney.com has introduced a new feature this week. Borrowers can now offer a car as collateral for a p2p loan.

The user pays a fee of 9.95 Euro to document this in his loan listing. Pictures of the car, the model and the mileage and the estimated price a car dealer would pay for car are displayed in the listing. In this example listing, the borrower puts up his BMW as collateral. The estimated value covers 101% of the loan amount requested. In general the car can cover any percentage of the loan amount – it does not need to cover the full amount. Furthermore there is information on the type of insurance coverage.

If the loan is funded, then a contract defines the terms of the assignment as security. The borrower continues to drive the car (obviously he is not allowed to sell it without the consent of Auxmoney), but needs to deposit the certificate of ownership (motor vehicle registration certificate) at Auxmoney. This arrangement costs the borrower 2 Euro per month.

Should the borrower fail to repay the loan, then Auxmoney has the right to sell the car.

While a car as collateral does in not provide fail-safe security (many things can happen), it will be probably perceived by lenders as one feature for higher security against defaults.

The Wiseclerk Auxmoney stats page will in future track the performance of p2p loans secured by cars.

This is a first for p2p lending – but soon another p2p lending service will follow. Pärtel Tomberg, CEO of Estonian p2p lending service Isepankur told P2P-Banking.com earlier this month, that Isepankur will introduce cars and real estate as collateral for p2p loans in the second half of 2010.

(Photo by pedrosimoes7)