Greennote – p2p student loans at a fixed low interest rate

Greennote.com will offer p2p loans to help college students pay for their education. Unlike at the competitor Fynanz, at Greennote interest rates are equal for all loans – at launch 6.8%.

Greennote puts a lot of trust in students. All that's required is a school id. No credit checks.
From the Greennote Lender FAQ:

Q: Is there any collateral for the loan? Does the student go through a credit check?

No collateral is provided. This is an unsecured loan. And there is no credit check for the student. You are making this loan because you are helping your student and believe in his or her potential. It’s an investment in someone’s future. At the same time, this is not a handout and you will receive a return on your money.

However, as with any loan, there are risks involved. GreenNote cannot guarantee the repayment of any loan. If a student is unable to repay the loan and defaults after leaving school, GreenNote will provide collections services. We will report delinquencies to credit agencies, which will impact the student’s ability to get credit in the future.

The terms sound certainly attractive for students, especially for those with a low or no credit grade. Students can defer payments while in school:

Payments begin six months after the student finishes (or leaves) school. The student can also defer payments for the entire time he or she is enrolled in school, for up to a maximum of five years.

Student then have 10 years to pay back the loan. They can pay it back early any time without a penalty.

Whether this model appeals to lenders remains to be shown. A slogan on the site says: "Help students you know" – so Greennote is targeting relatives and friends who lend to students.

According to TechCrunch, Greennote raised 4.2 million US$ venture capital from Menlo Ventures and Glenbrook Partners last year.
Demand at Boober NL slows

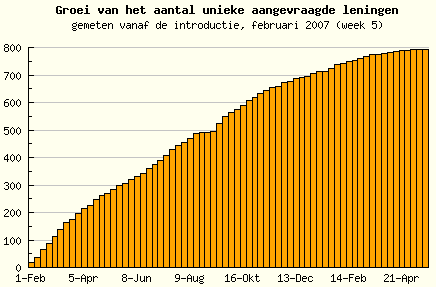
Demand at Boober.nl is slowing. When I checked today only two loan listings were open. The following curve showing unique loan requests definitly shapes in the wrong direction. Boober lenders discus this development in this forum thread.


(Source Booberwatch.nl)

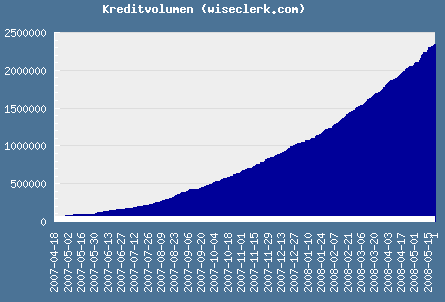
Since the launch 15 months ago, about 2.4 million Euro (about 3.8M US$) loan volume has been funded through Boober.

German Smava.de has funded about the same volume (2.3 million Euro) but after a slower start 14 months ago, lately the volume growth accelerated moderately.

Smava loan volume
(Smava loan volume, Source: Smava loan stats at Wiseclerk.com).

On Smava as well as on Boober average borrower interest rates have risen considerably since the start. This reduces the attractiveness for borrowers.

Advanta doubles funds to Kiva loans

Credit card issuer Advanta entered into a partnership with Kiva. The initiative is called KivaB4BProject and Advanta will match the loans made by business card holders with up to 200 US$ per card. Card holders simply select a business owner to sponsor through Kiva and make a grant using their Advanta Business Card. Advanta matches that grant, dollar for dollar, and Kiva distributes the total resulting funds.

The loans funded by this project can be seen on this Kiva lender page. Already contributed to more than 500 loans.

When the project was announced at Advanta's headquarters, Advanta flew in Kiva borrower Senerita Lilli a dressmaker from Samoa to share her story. 

MyC4 – first issue of CHANGE magazine

MyC4 has just published a quarterly magazine to accompany it's website. The first issue of Change has 20 pages, looks stylish and has lots of information (e.g. Senegal will be the next market, where loans are available to borrowers starting in June). Here is what MyC4 says about it's magazine:

We have just released the very first issue of CHANGE – the magazine that comes all way around MyC4: Vision, business model, partners, supporters, etc.